Latest from BCA Research
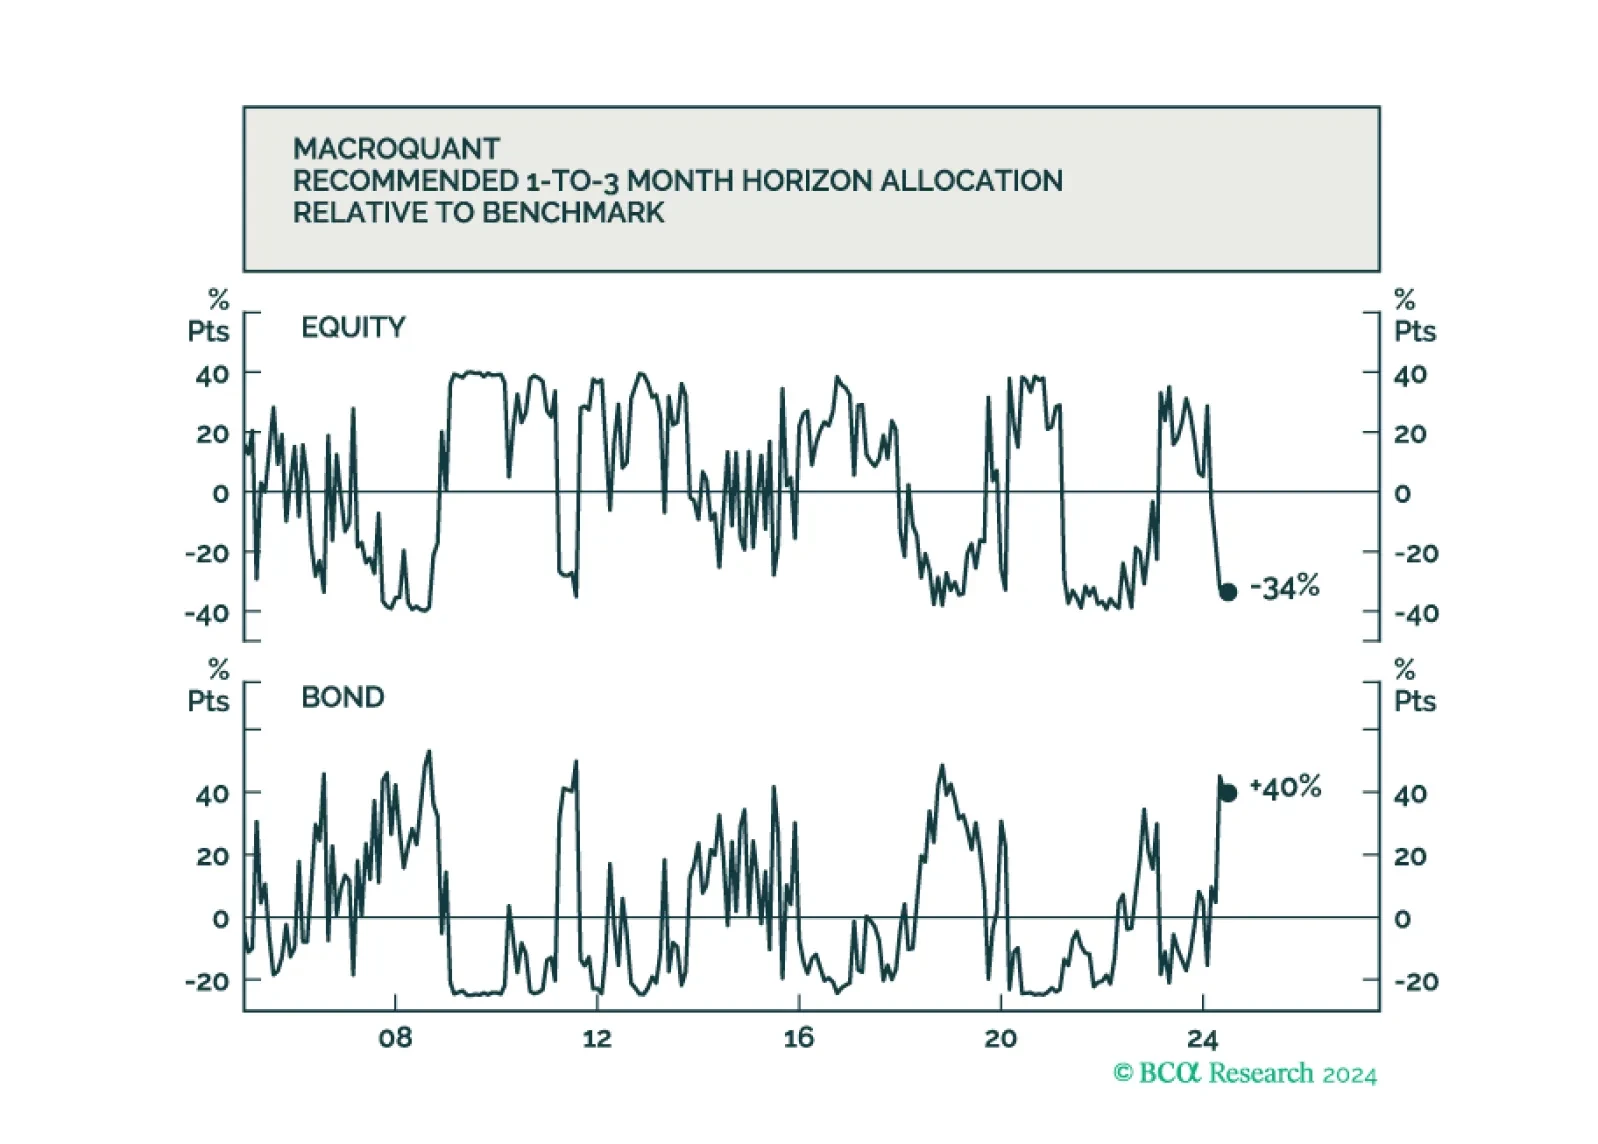
The Global Investment Strategy team downgraded global equities to underweight in late June. The latest reading from our MacroQuant model is consistent with this decision.
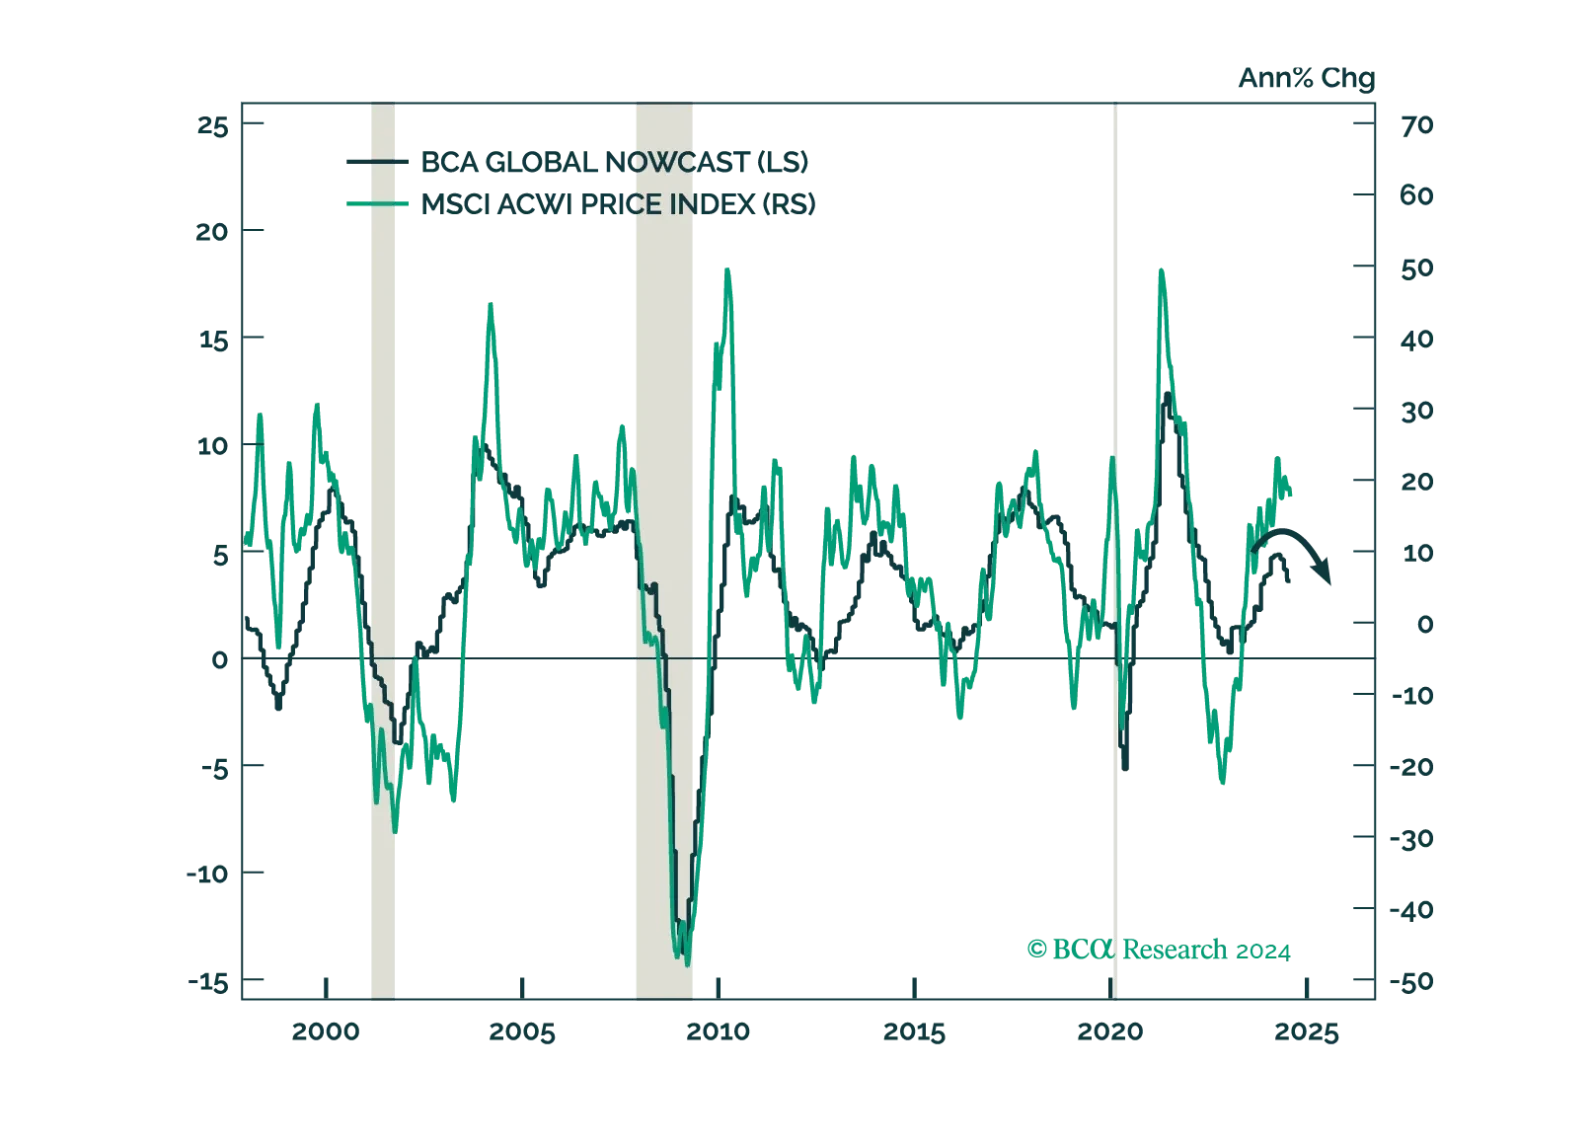
The market is pricing in a soft landing, but we see growing signs that the global economy is faltering. Investors should be defensively positioned.
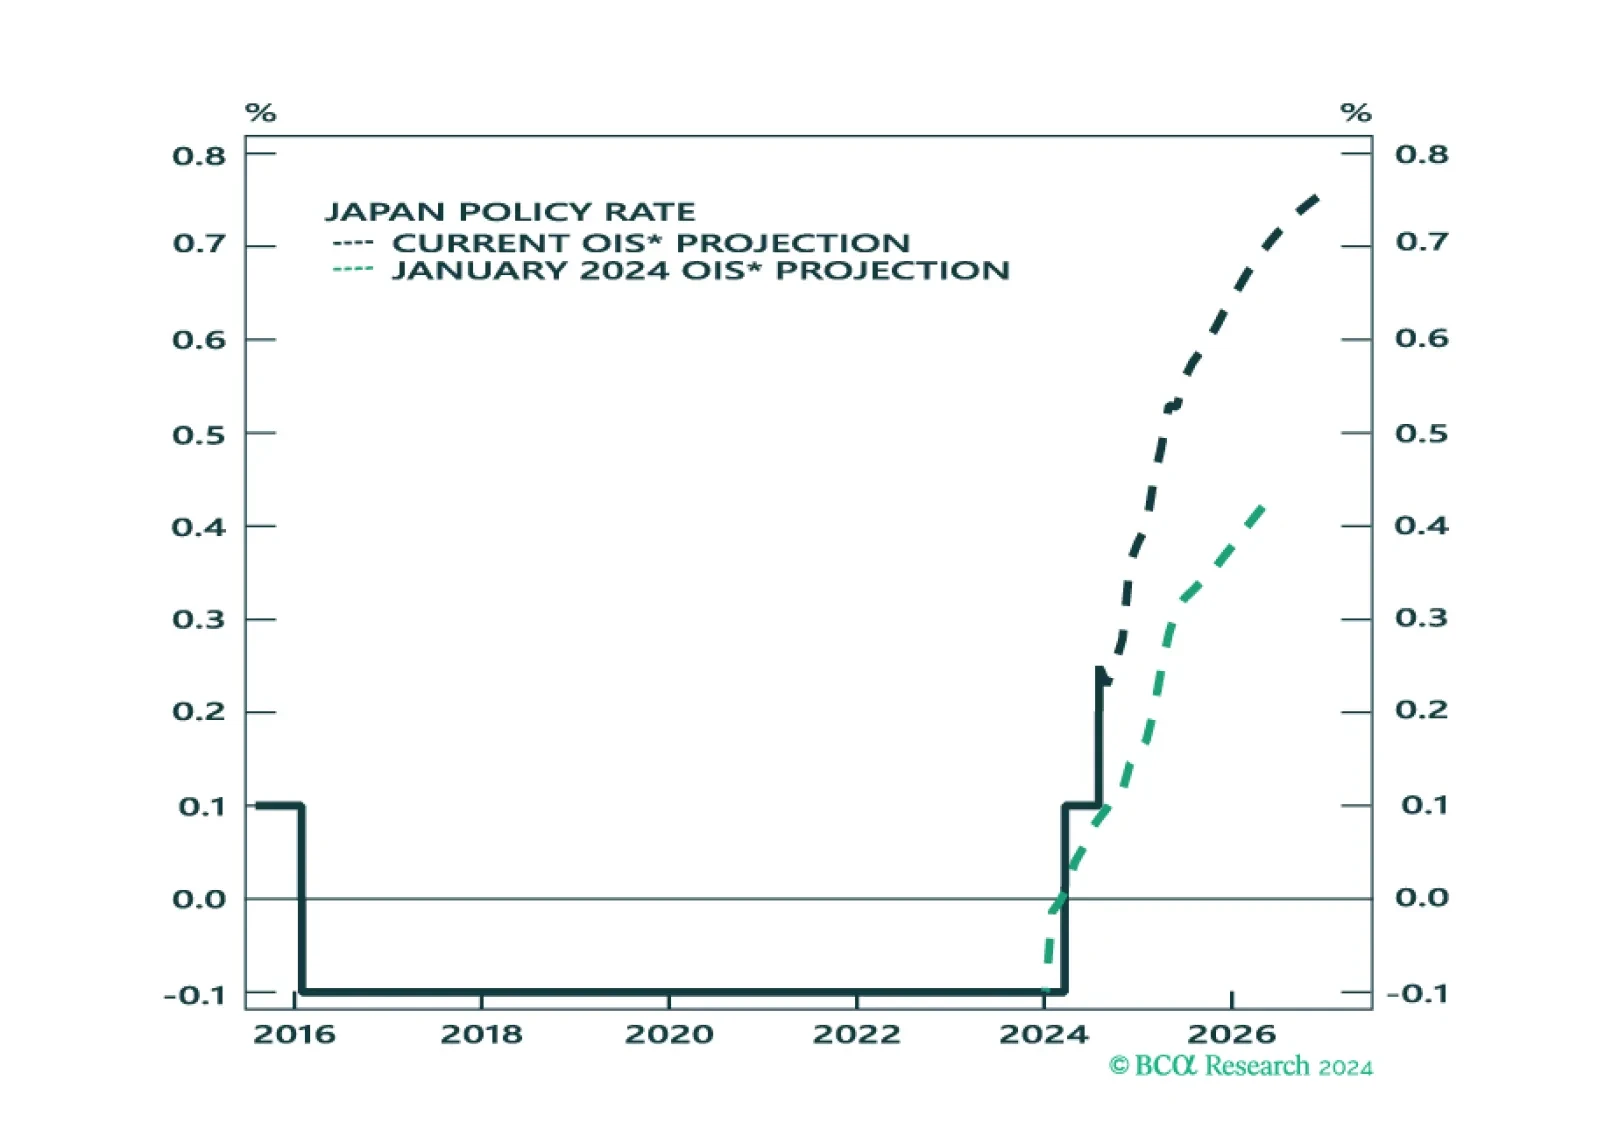
We assess the investment implications of the BoJ and Fed meetings, and give our take on the next policy moves. We also assess the impact on asset markets.

The Fed kept rates steady today, but teed up an initial rate cut in September while putting more emphasis on the employment side of its dual mandate.
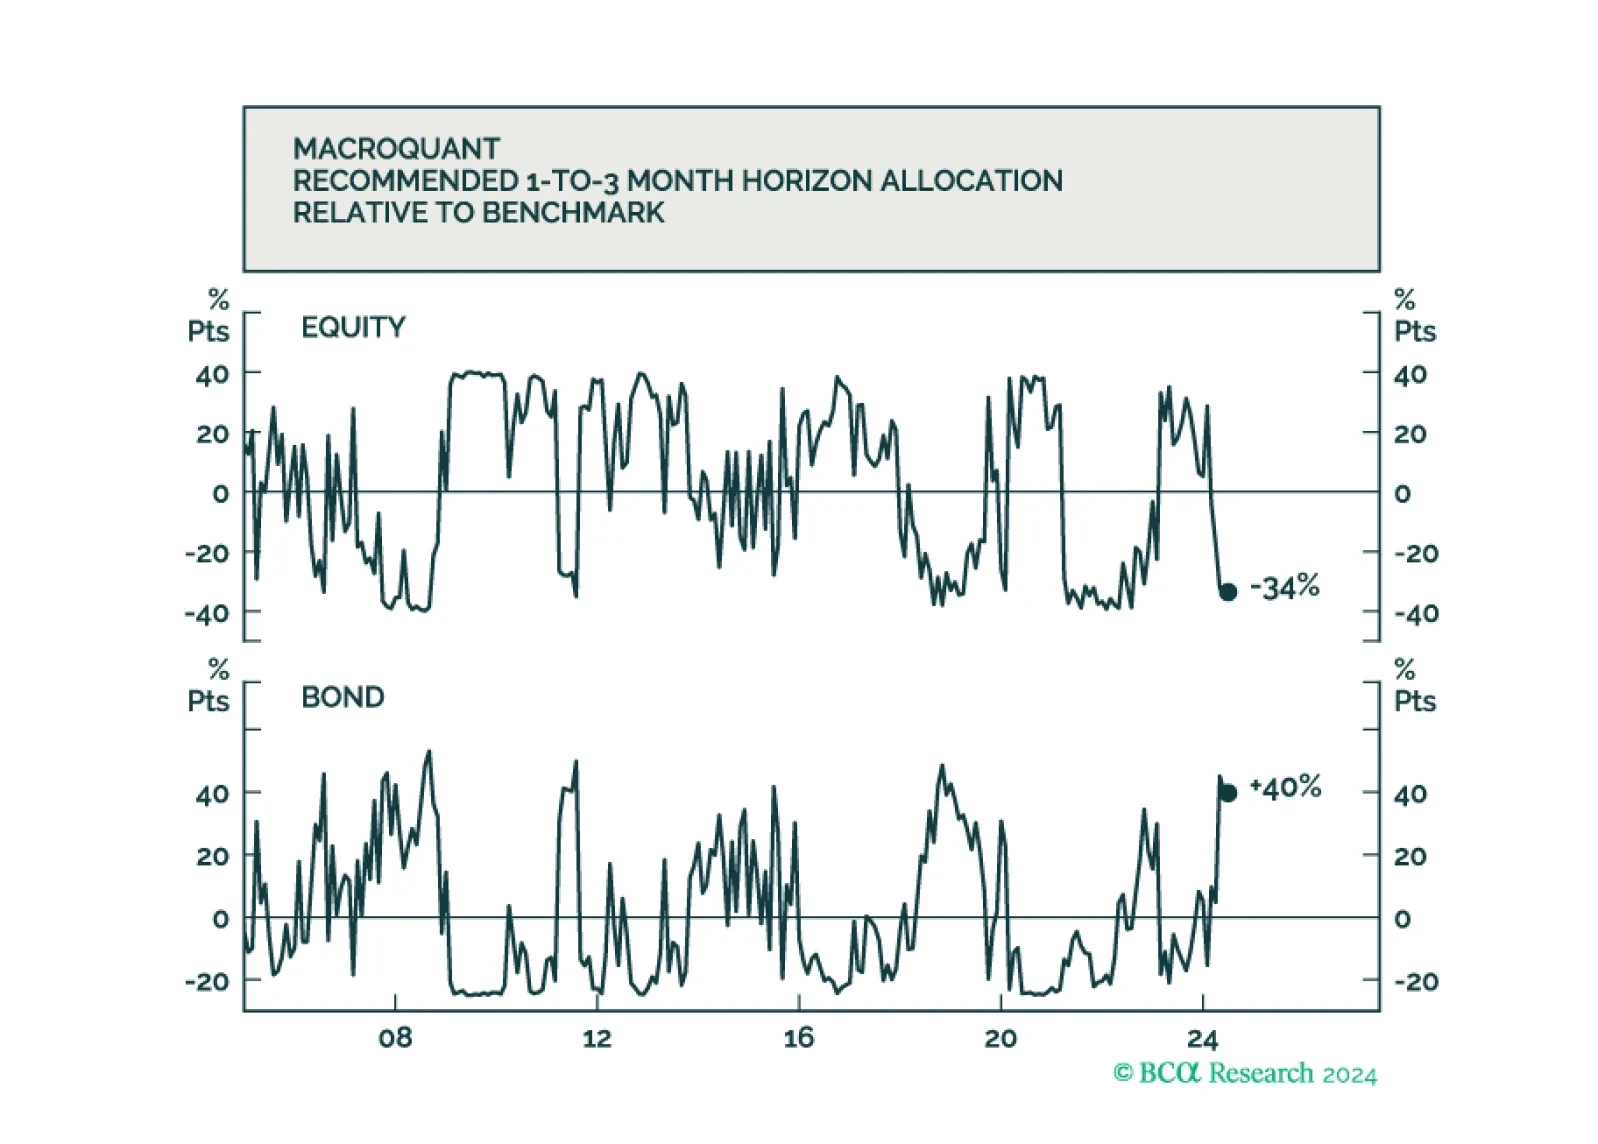
The Global Investment Strategy team downgraded global equities to underweight in late June. The latest reading from our MacroQuant model is consistent with this decision.
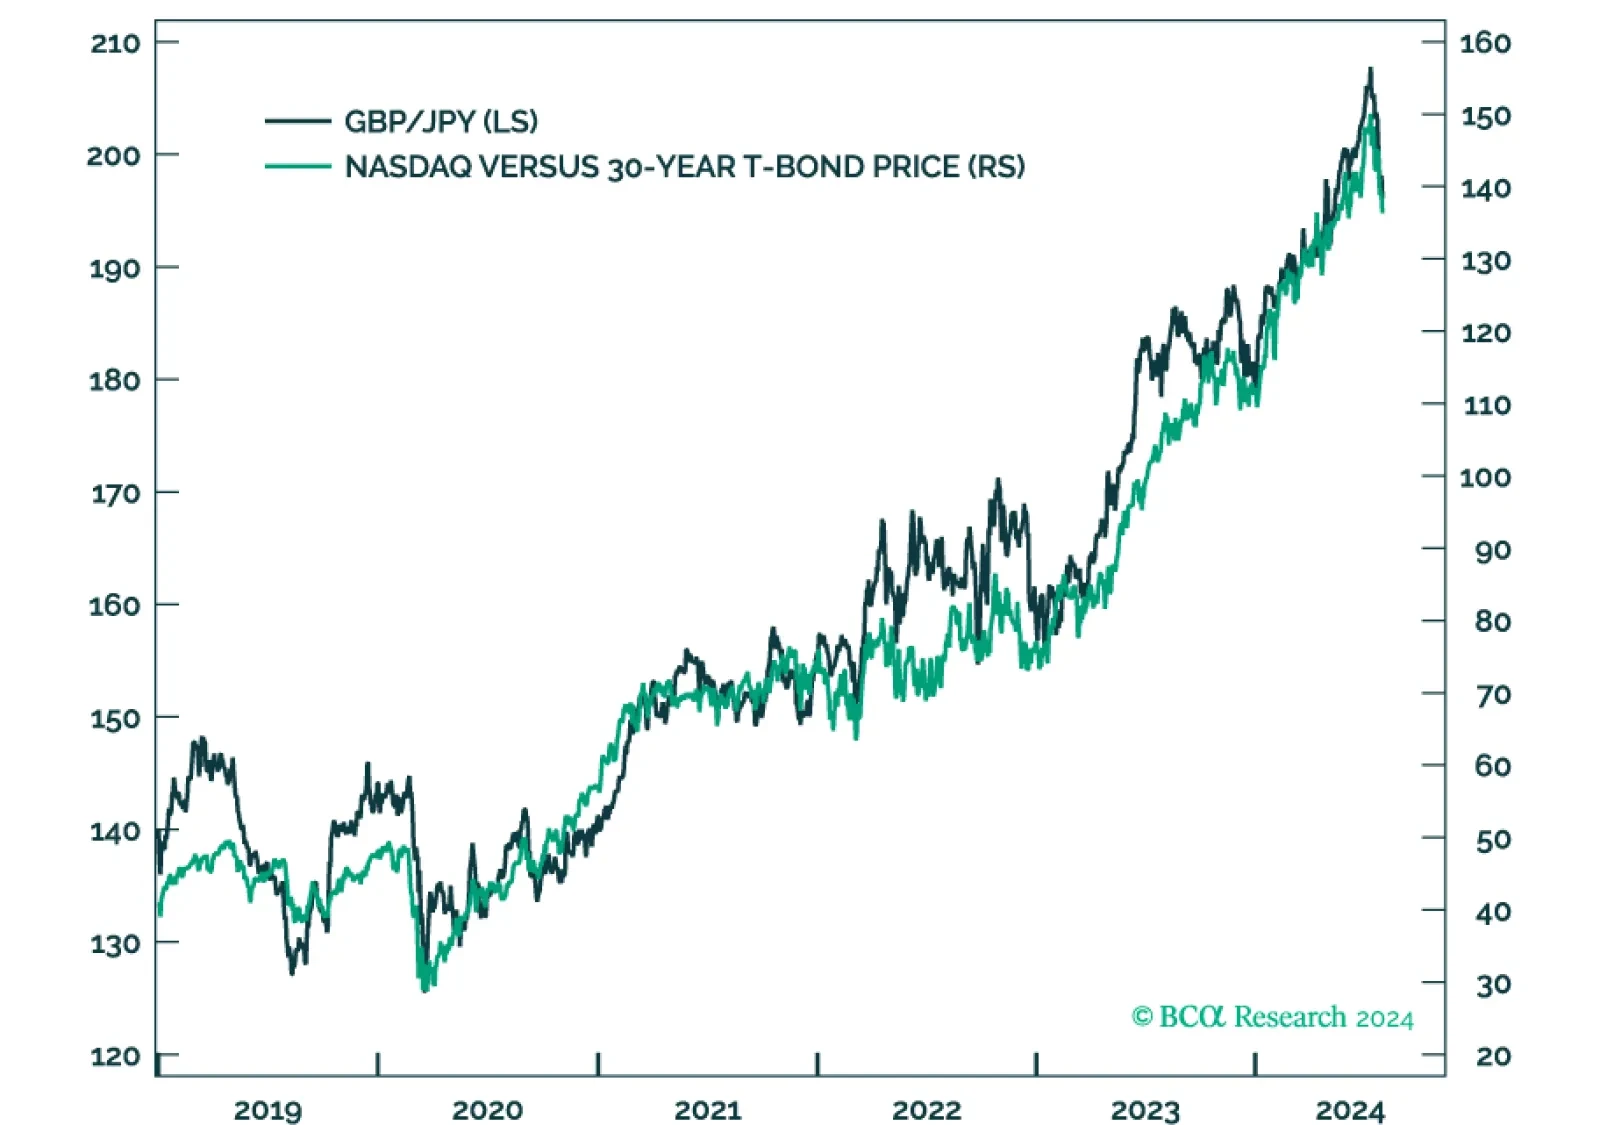
We should fear a recession in the frothy parts of the US stock market much more than a recession in US GDP. And as frothy US tech stocks sell off, an excellent hedge is to go long JPY/GBP or JPY/EUR.

The war in the Middle East is expanding, upgrading our subjective odds of a major oil supply shock to 37% and underscoring our 60% odds of Republican victory in November. Volatility should spike again as investors contemplate the prospect of rising oil prices amid slowing US and global growth. Tactically investors should stay overweight energy stocks relative to other cyclicals and favor oil producers in the Americas rather than Middle East.
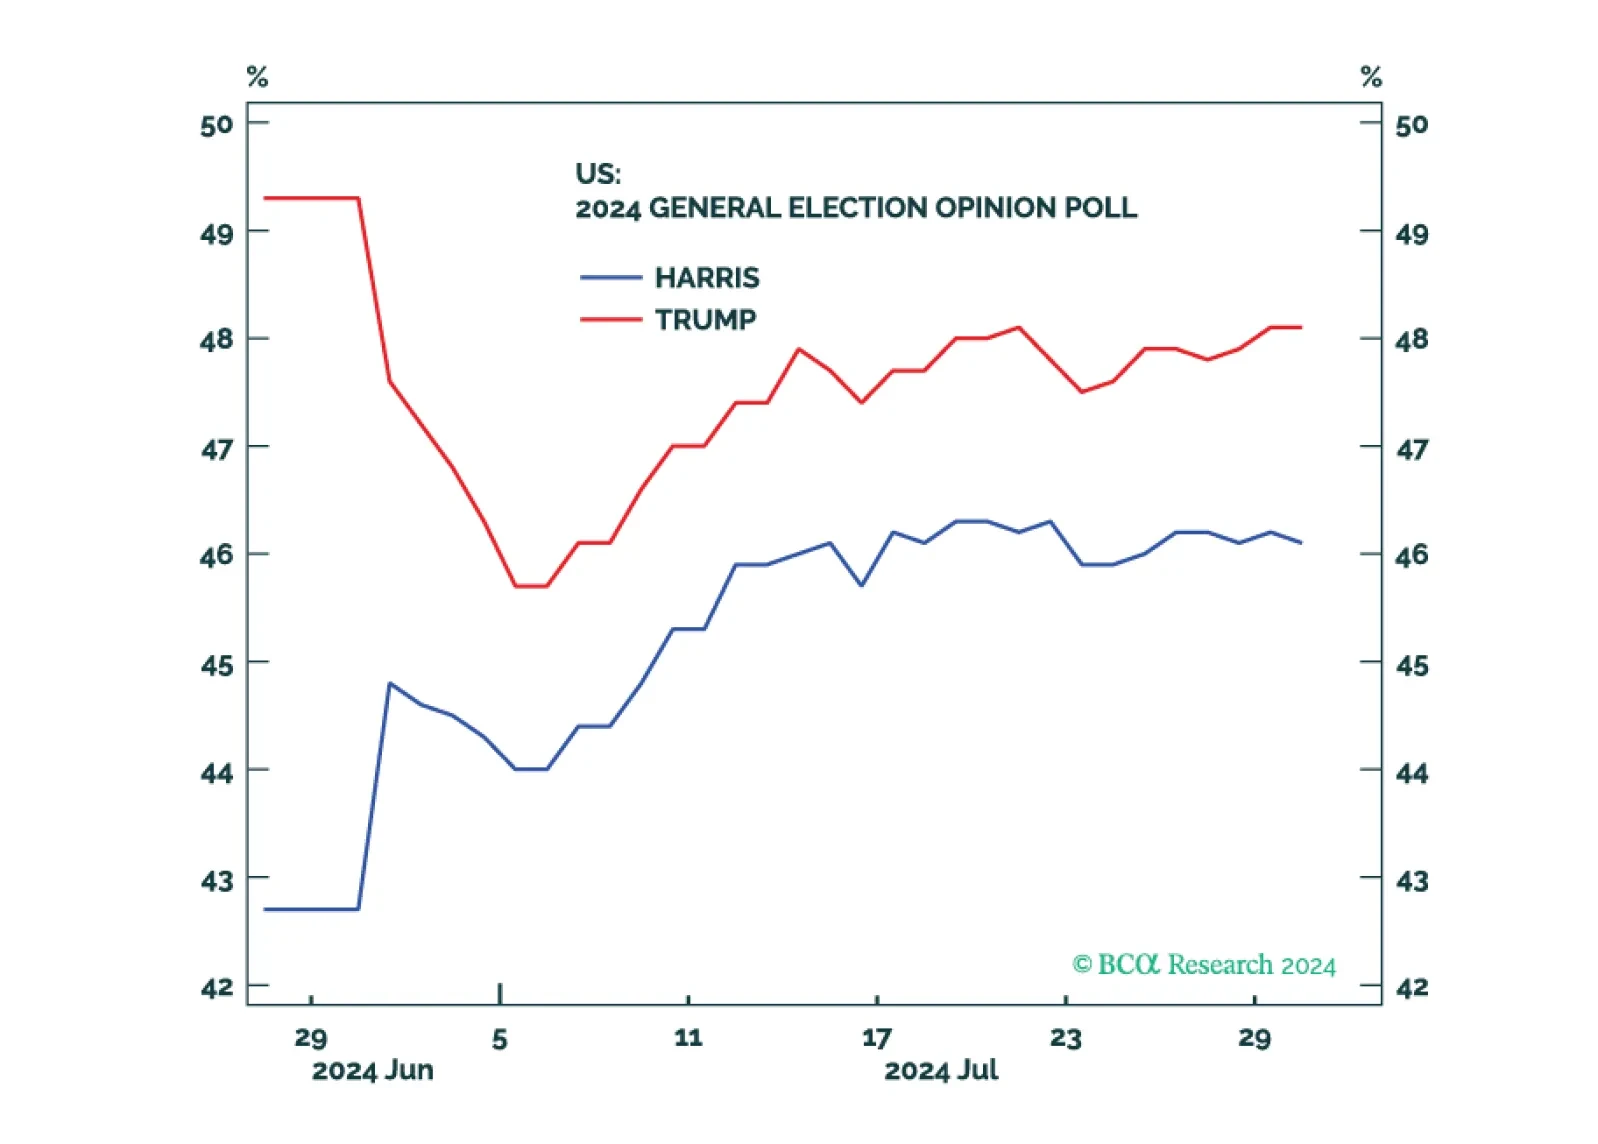
Republicans are favored but the election is still competitive. Equities, corporate credit, and cyclical sectors will fall until policy uncertainty is reduced.