Latest from BCA Research
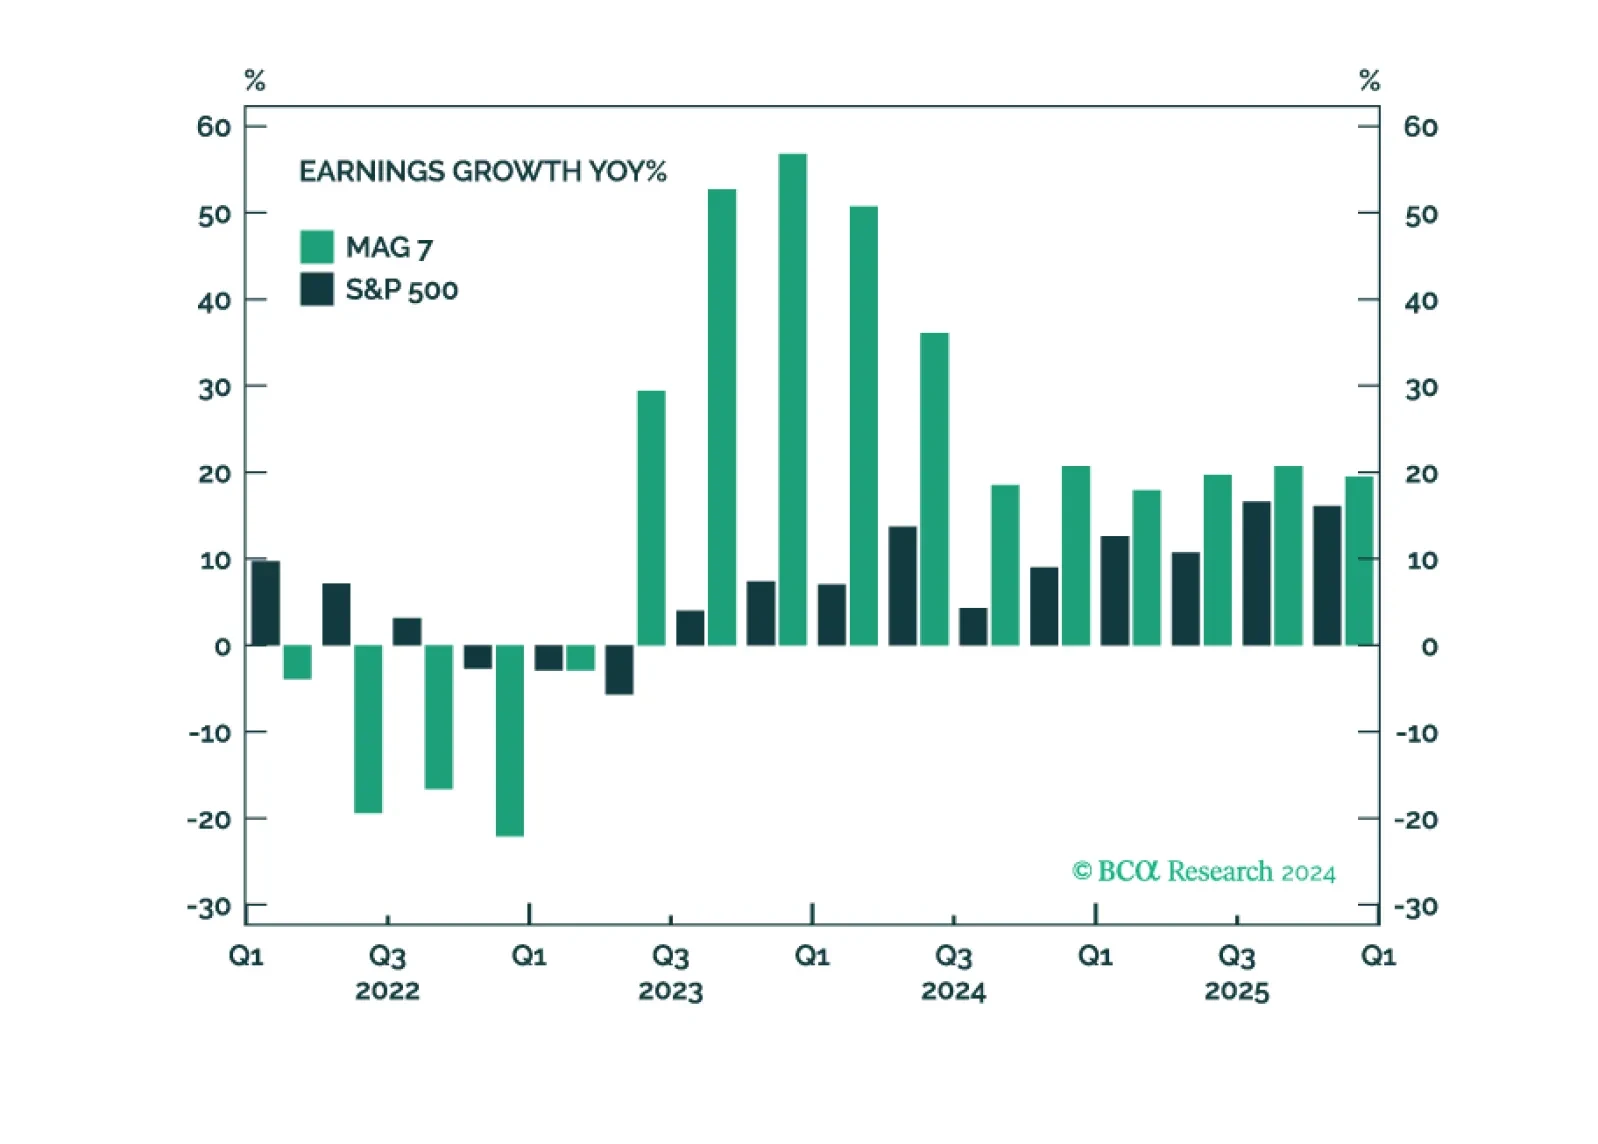
This week, we are sending you a sector chart pack. In the front section of this publication, we briefly review October's performance and then switch our attention to the earnings season and outlook for the Magnificent Seven.
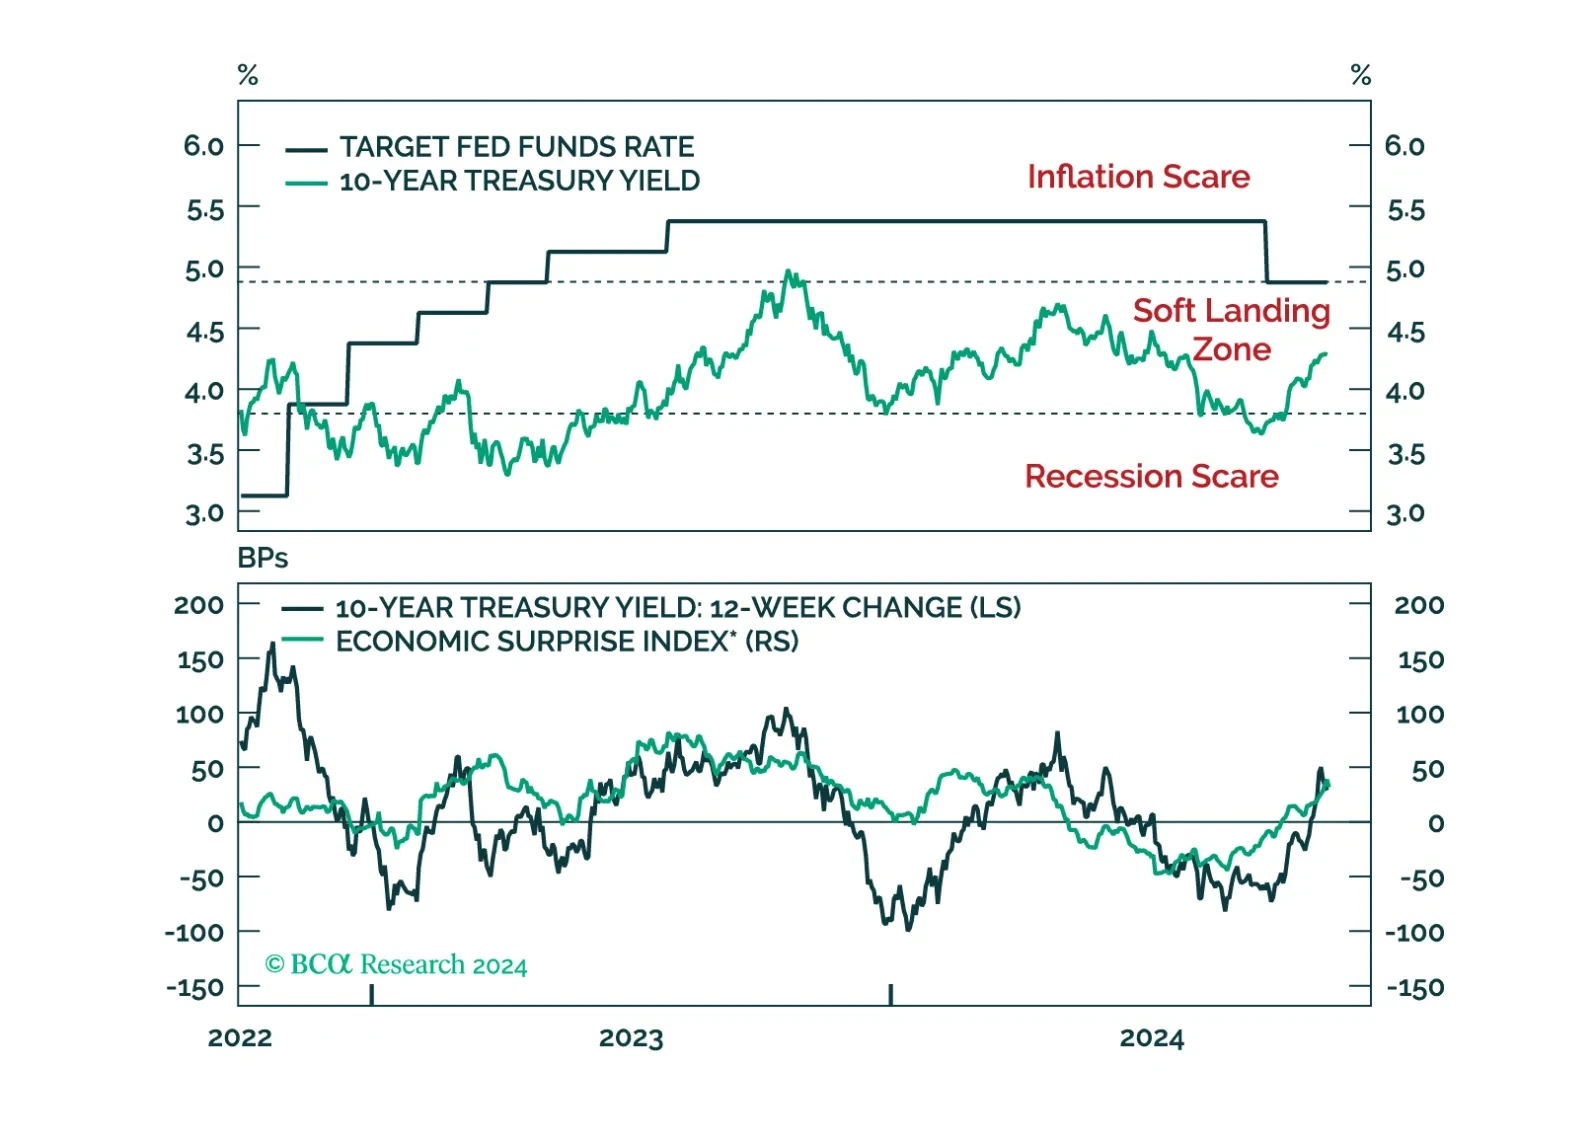
A reaction to this morning’s employment report and a preview of the potential bond market implications of next week’s US election and FOMC meeting.
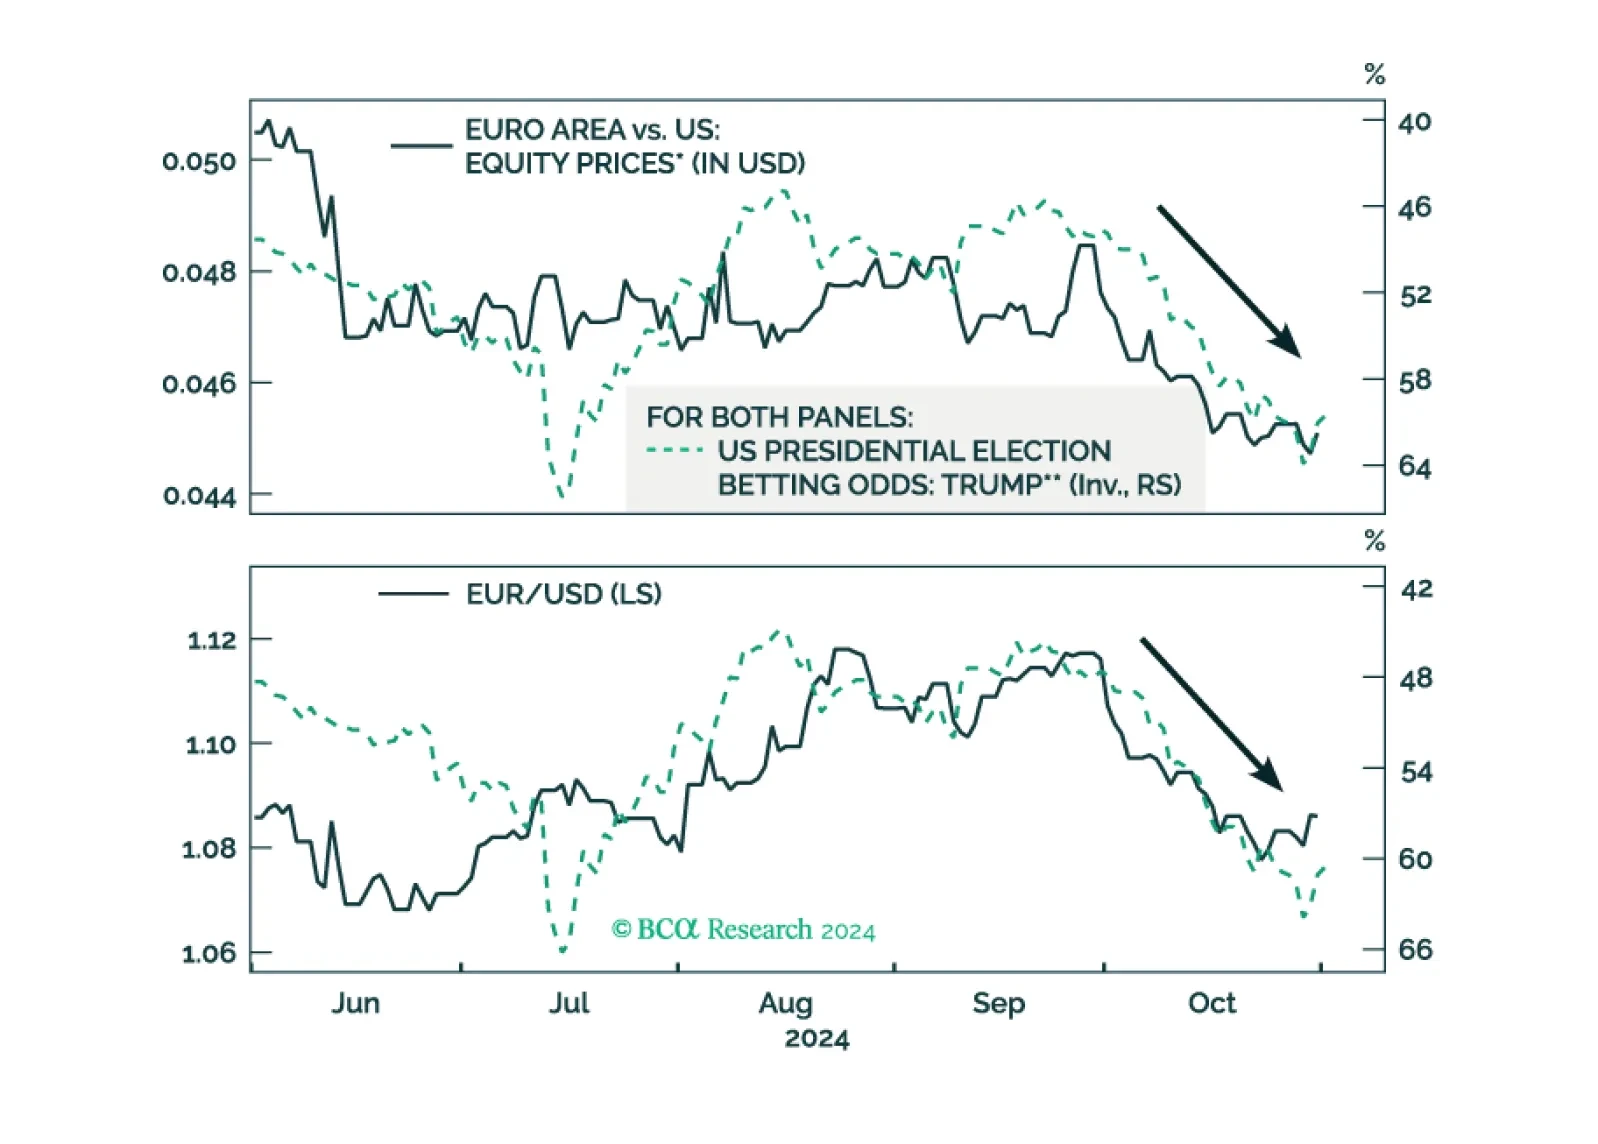
As the odds of a Trump victory rise, European assets underperform US ones. What would be the immediate impact of a Trump victory on European stocks?

Can Powell achieve a soft landing? There are some indications he is doing it. We examine why our negative stance was wrong and analyze the four growth engines that kept recession at bay. Half of these forces remain while the other half have run out of juice. While this might be enough to keep the economy going, we maintain our defensive positioning. Equities have priced a very benign outcome. Meanwhile, rising rates in anticipation of a Trump win are pushing the economy away from the soft-landing path. We hedge the possibility of further upside in yields in case Trump gets elected by downgrading duration to neutral.

MacroQuant expects global equities to weaken in November. As such, the model recommends underweighting equities and overweighting bonds and cash.
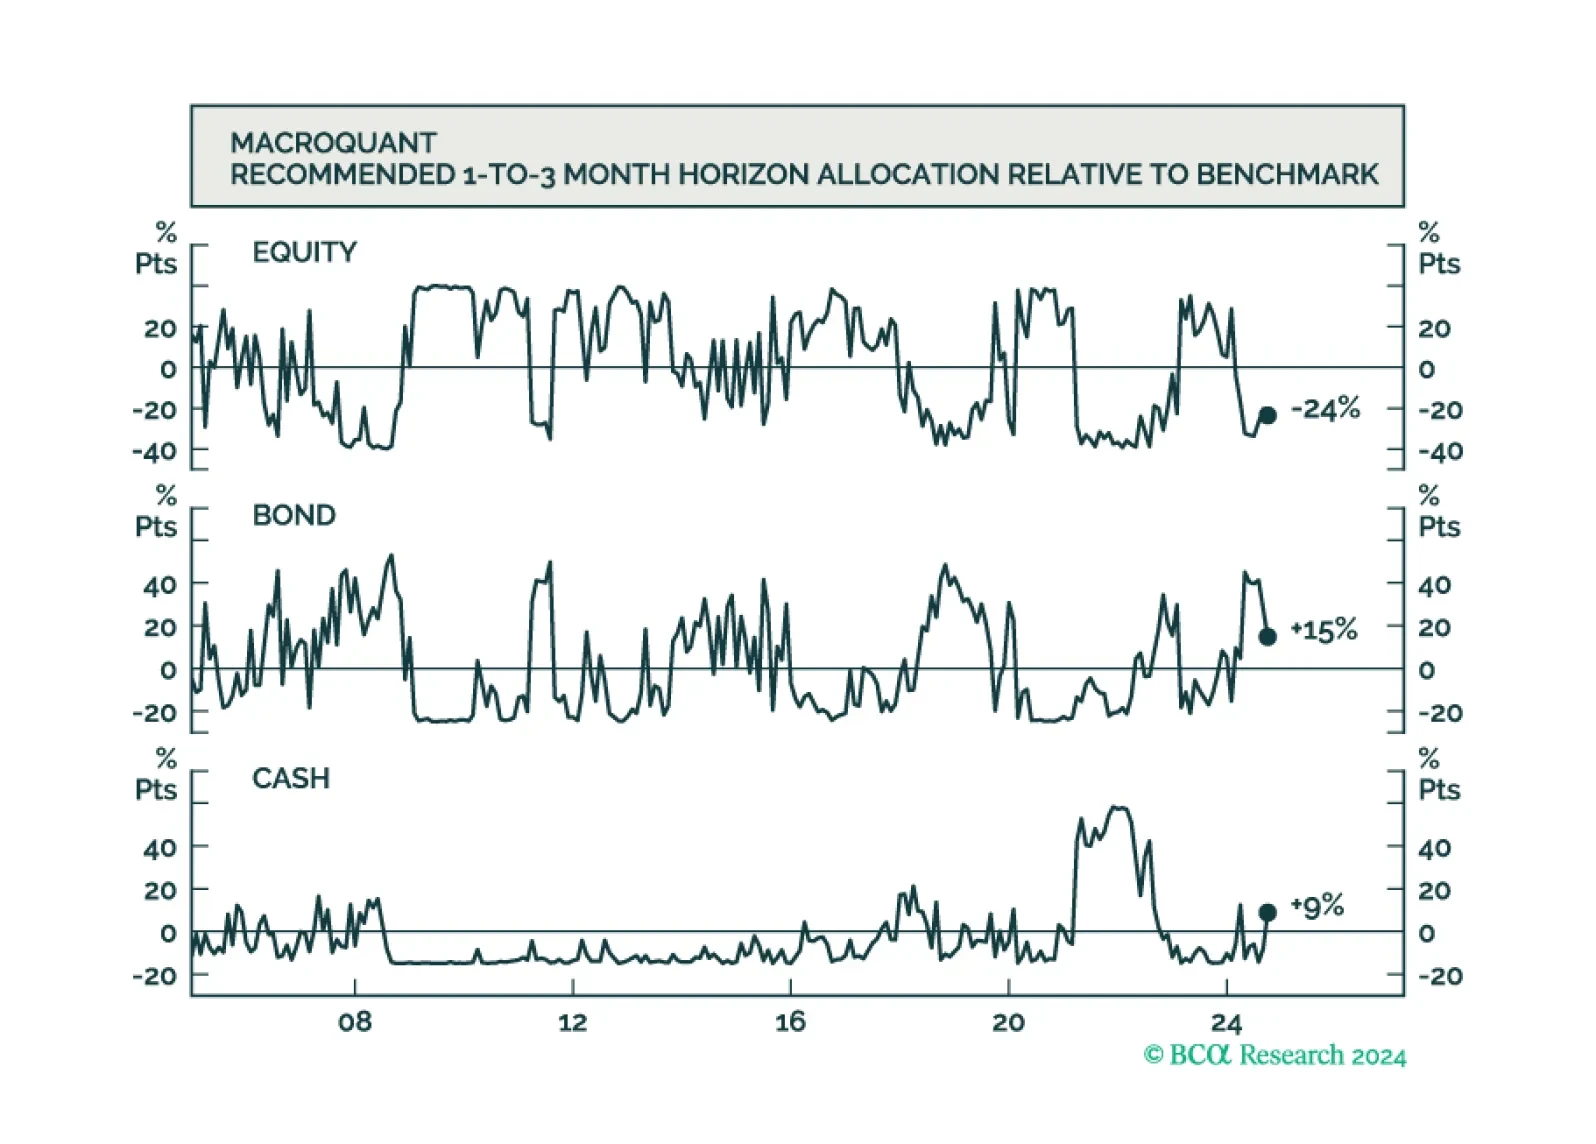
MacroQuant expects global equities to weaken in November. As such, the model recommends underweighting equities and overweighting bonds and cash.
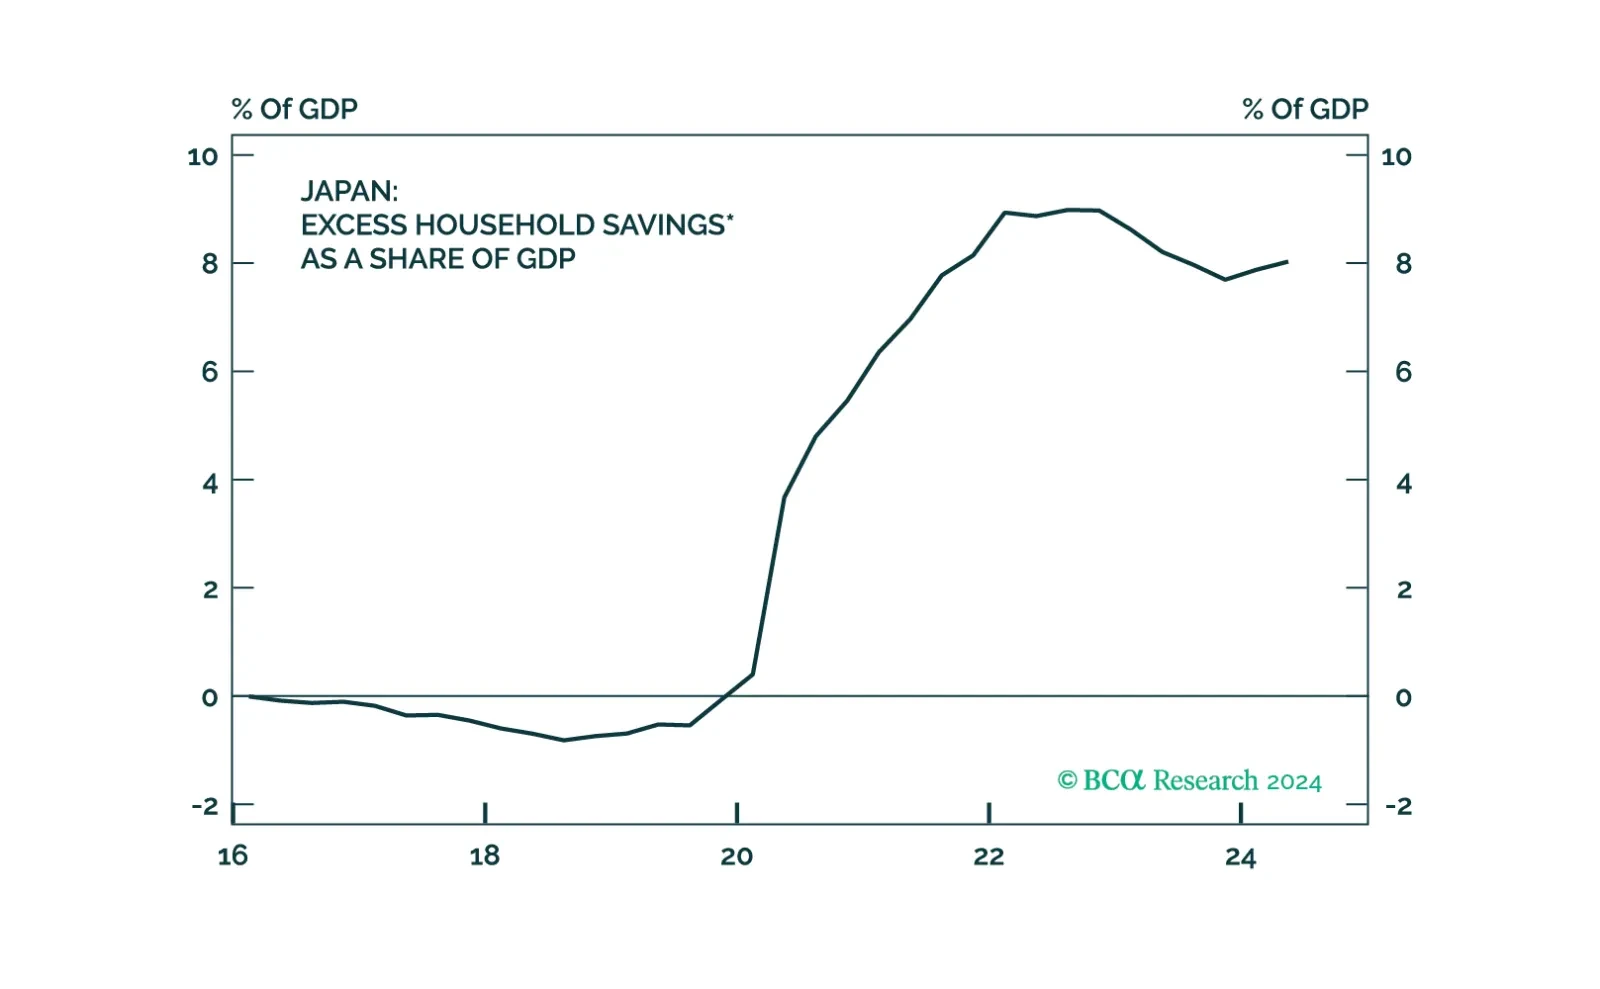
The latest Bank of Japan meeting did not alter our high-conviction views of being long the yen and underweight JGBs.