Latest from BCA Research
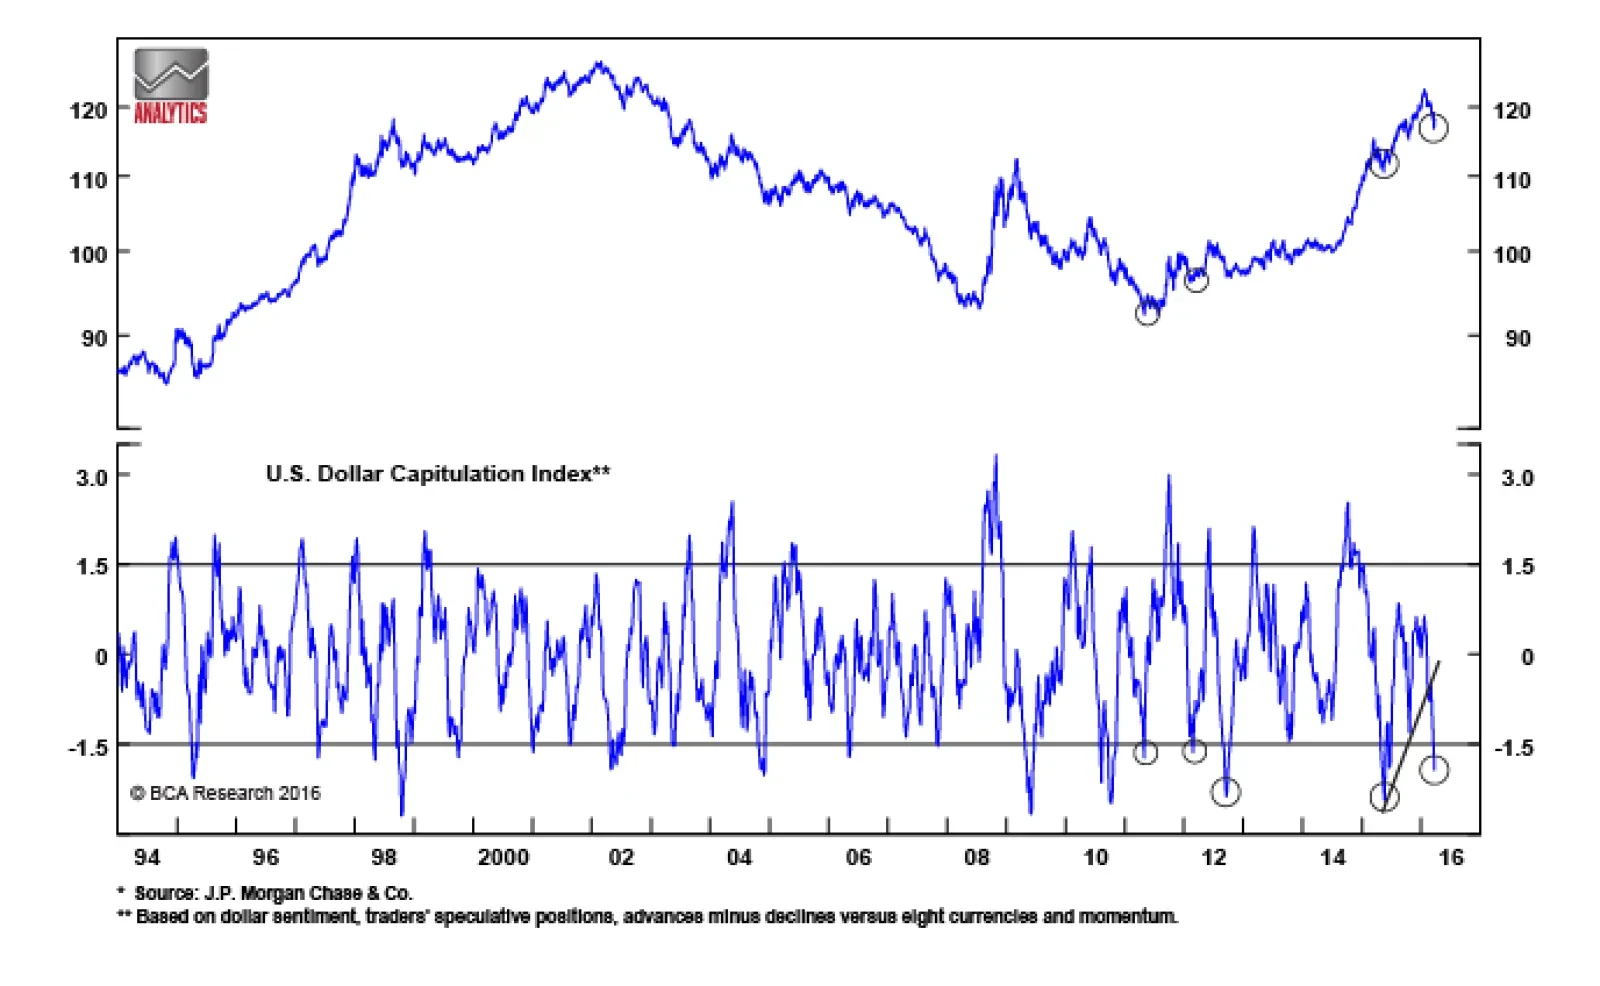
For the month of March, the model outperformed both global and U.S. equities in U.S. dollar terms. For April, the model has further pared back its equity risk exposure, shifting the allocation into cash. While Europe remains the largest equity overweight, there was a modest recalibration to defensive markets such as the U.S. and Switzerland. The allocation to EM was also nudged up a bit, on momentum and valuation grounds. In the fixed-income space, the model is sticking with U.S., Italian and Spanish paper.
The British pound may be prone to further weakness in the coming months as the odds of a Brexit rise.
Lower oil prices are aggravating financial and social stress in poorer OPEC states, particularly in Venezuela, where the government recently executed a gold-for-cash swap ahead of looming debt payments.
A global comparison suggests that China's capacity utilization does not appear particularly weak compared to other countries. The excess capacity problem is not unique to China, and therefore cannot be explained by China's investment-driven growth model. Chinese stocks have been unduly punished by the "overcapacity" stigma, which is unwarranted and will eventually correct.