Latest from BCA Research
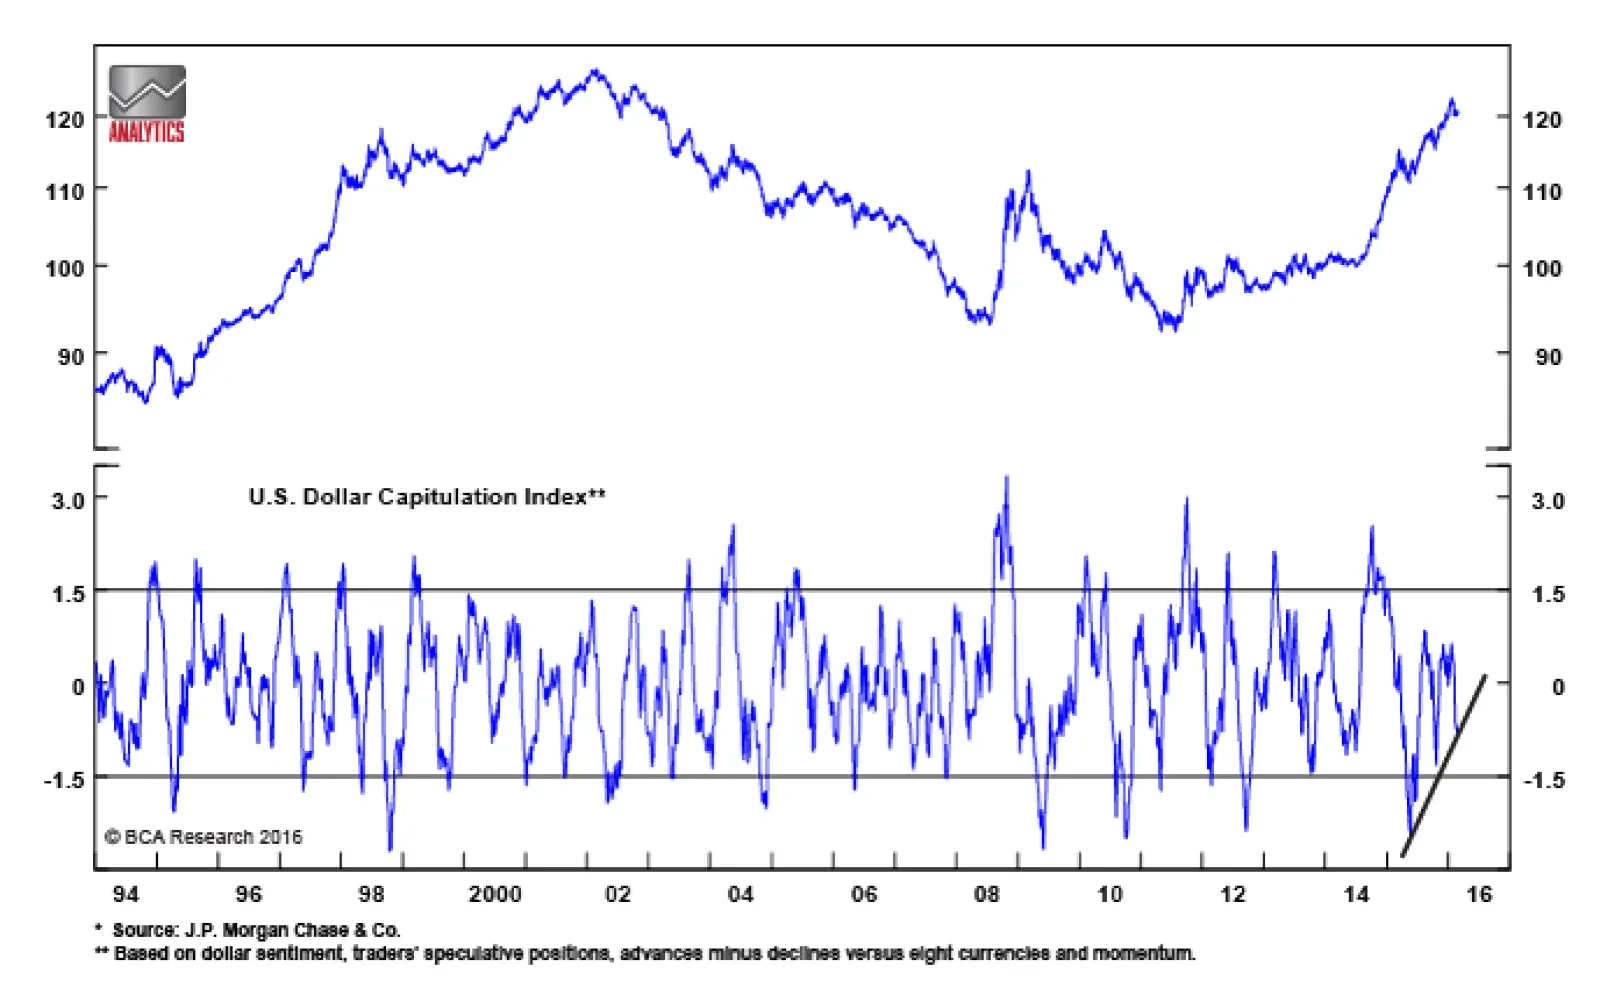
For the month of February, the model underperformed both global and U.S. equities. For March, the model has modestly pared back its equity risk exposure, shifting the allocation into bonds. While Europe remains the largest equity overweight, EM and Canada also received some allocation. The U.S. and New Zealand were slightly downgraded. In the fixed-income space, the model is sticking with Italy and Spain.



Sterling has come under intense pressure since PM Cameron announced date of the EU referendum. Our bearish view on the British pound has not been based on a forecast of U.K. succession from the EU.
The remarkable admission by OPEC's secretary-general, Salem el-Badri, earlier this week that with "any increase in (oil's) price, shale will come immediately and cover any reduction" in output only hints at the larger impact of light-tight-oil (LTO) going forward.
Where is the most likely mispricing of interest rates today? Plus our latest thoughts on the U.K.'s June 23 referendum on EU membership, and its market implications.