Data Center
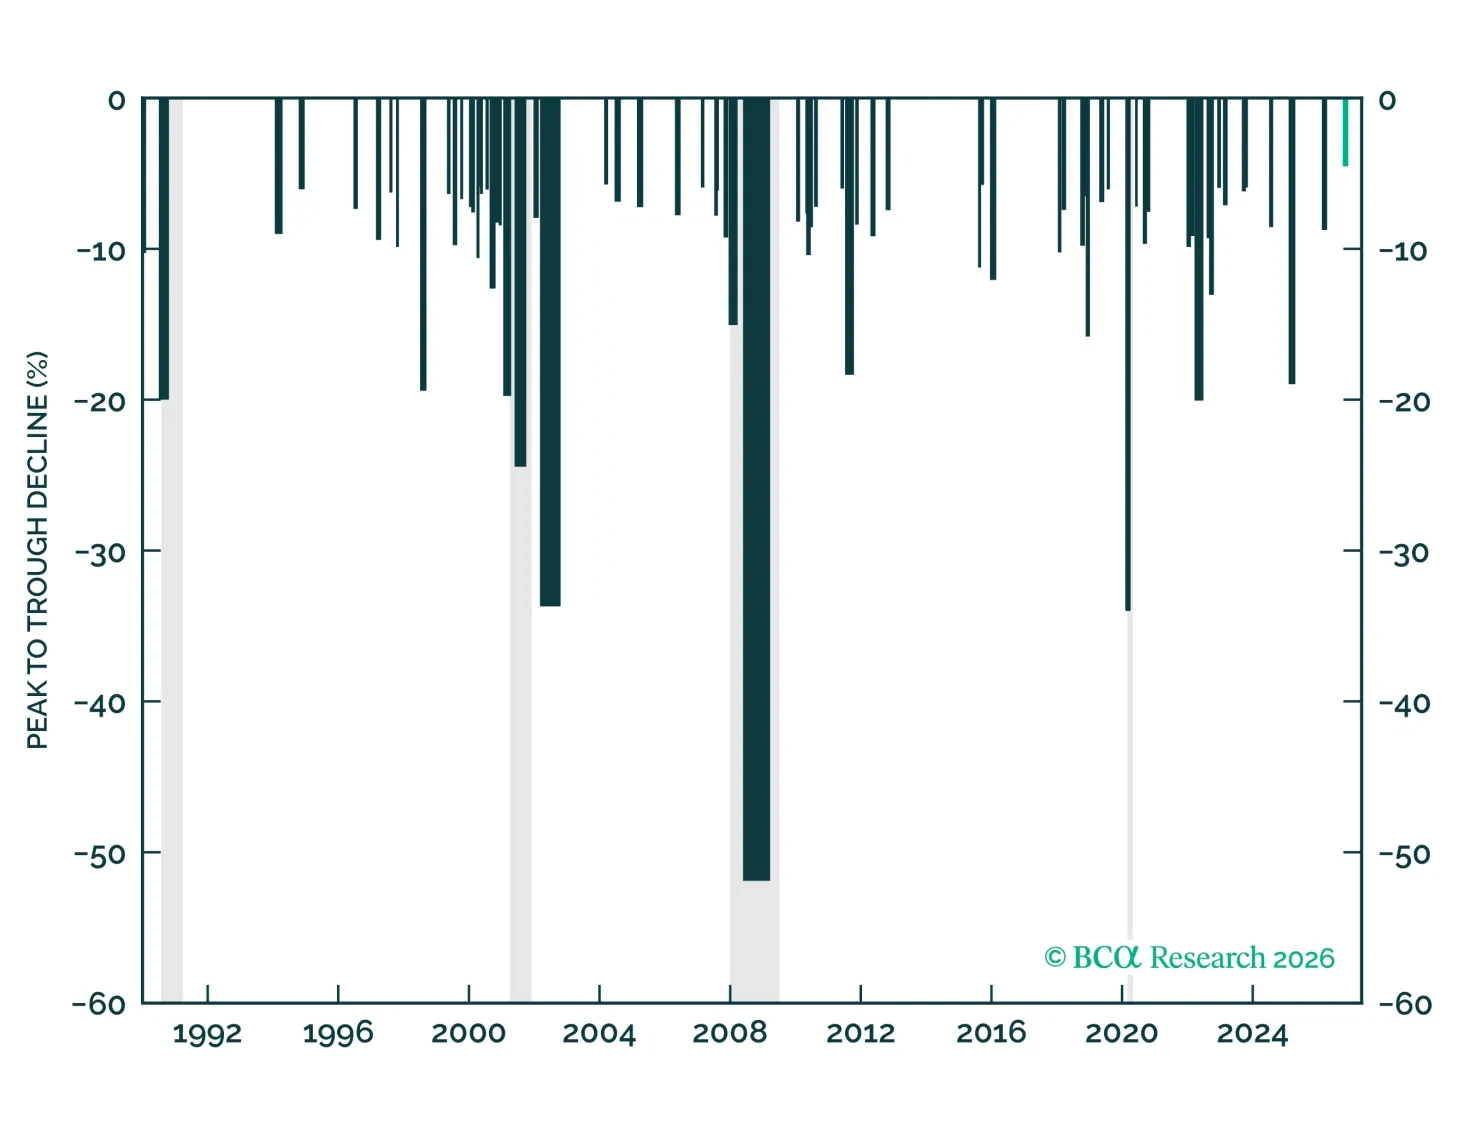
AI capex concerns have pushed the S&P 500 to the brink of a drawdown. But the cycle remains strong, drawdowns rarely last long, and Tech valuations had already compressed. And while Democratic governors now oversee about 80% of the data-center pipeline, a blue governor alone is not necessarily a build-out moratorium.
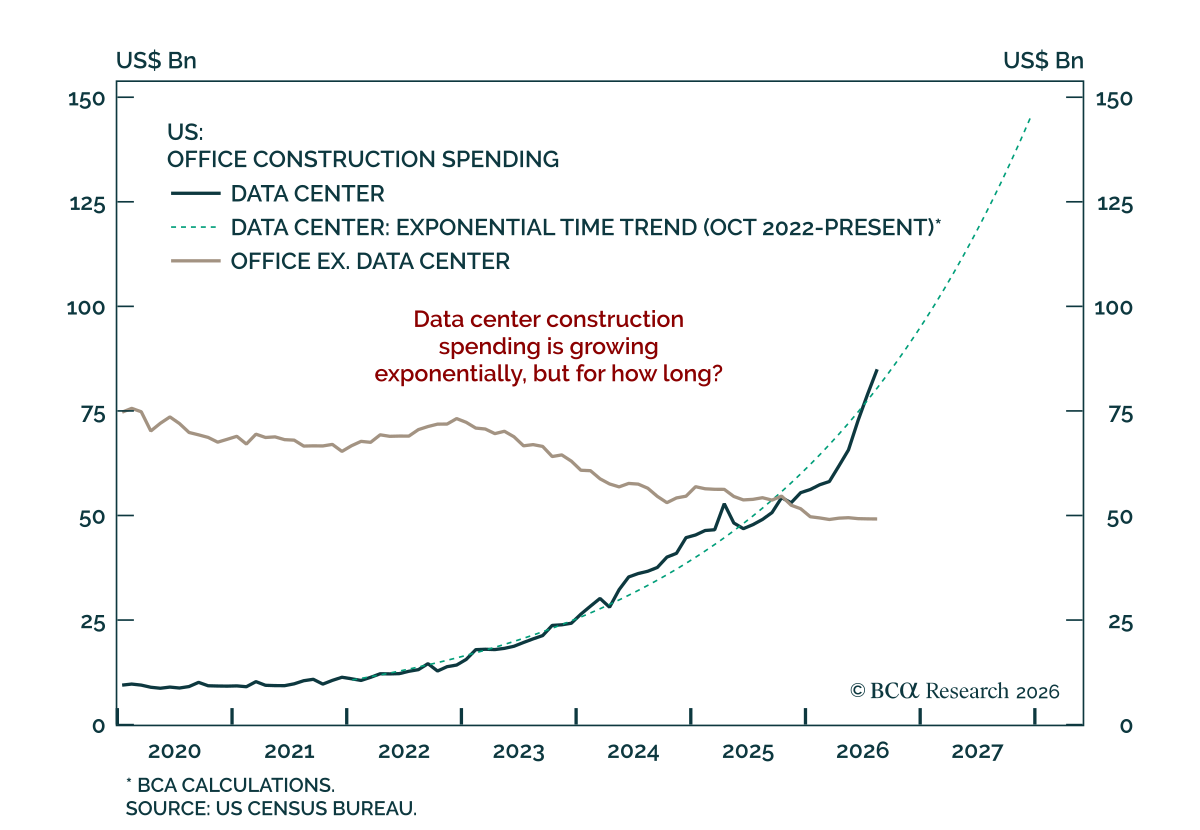
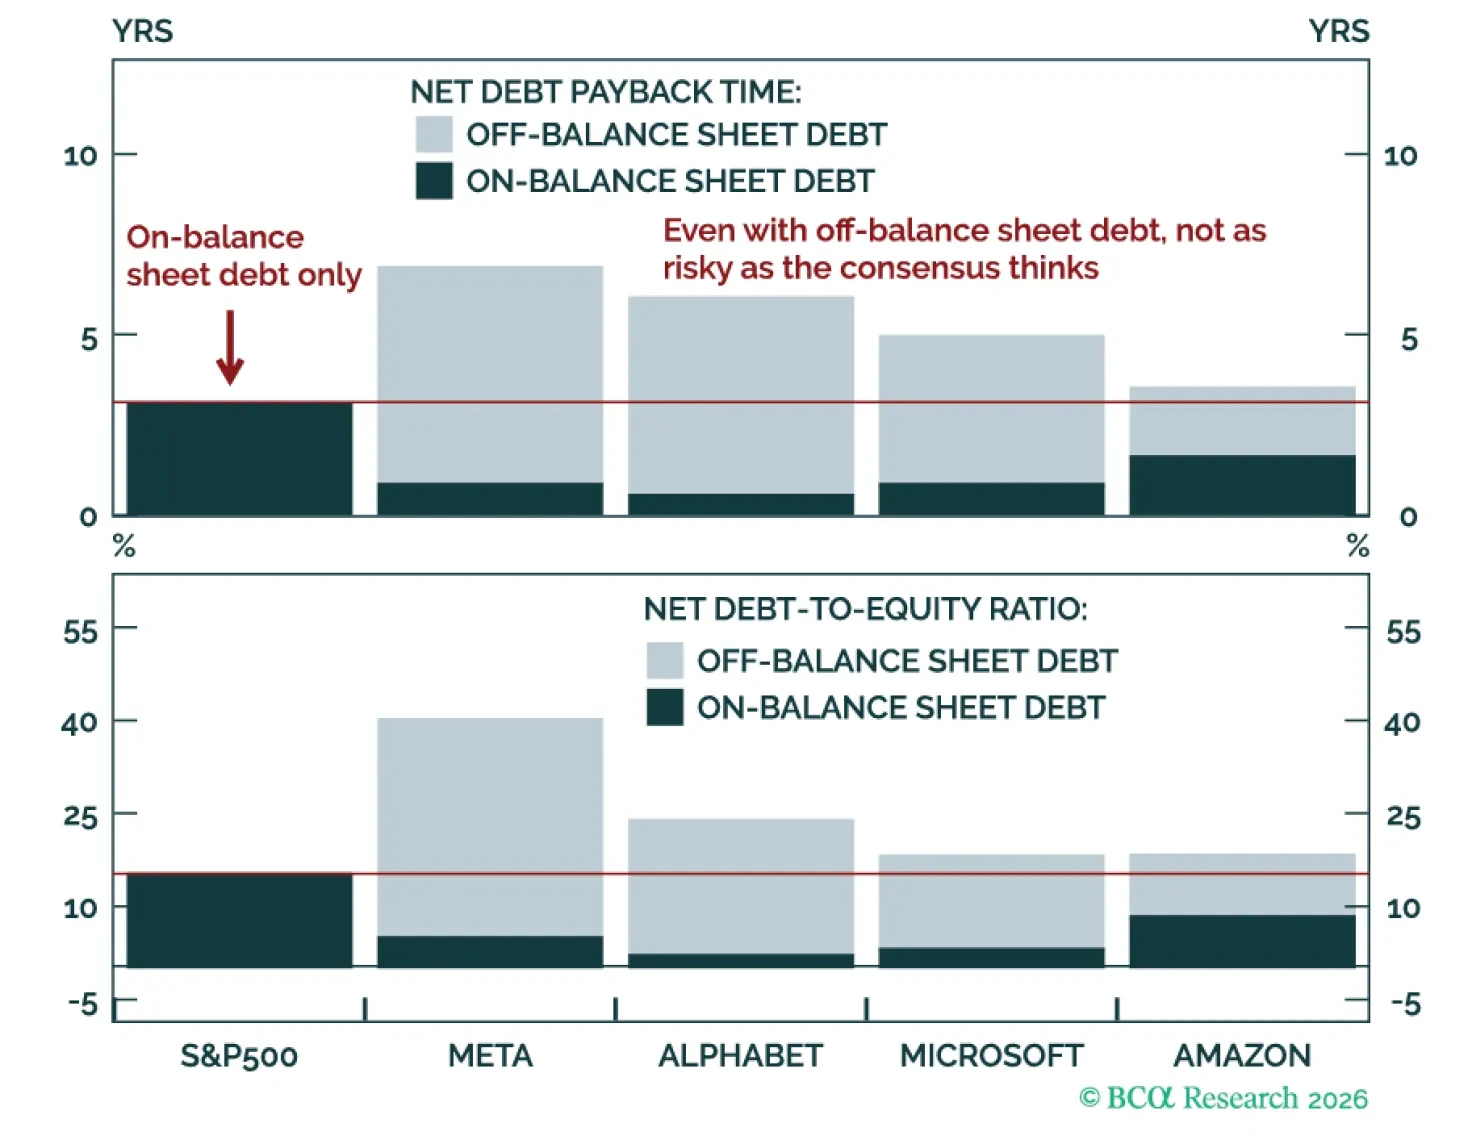
Nerves are rising around Data Center financing but most of the fear comes from GPU financing. GPUs are not Data Centers. Data Center collateral is solid, and so are the tenants.
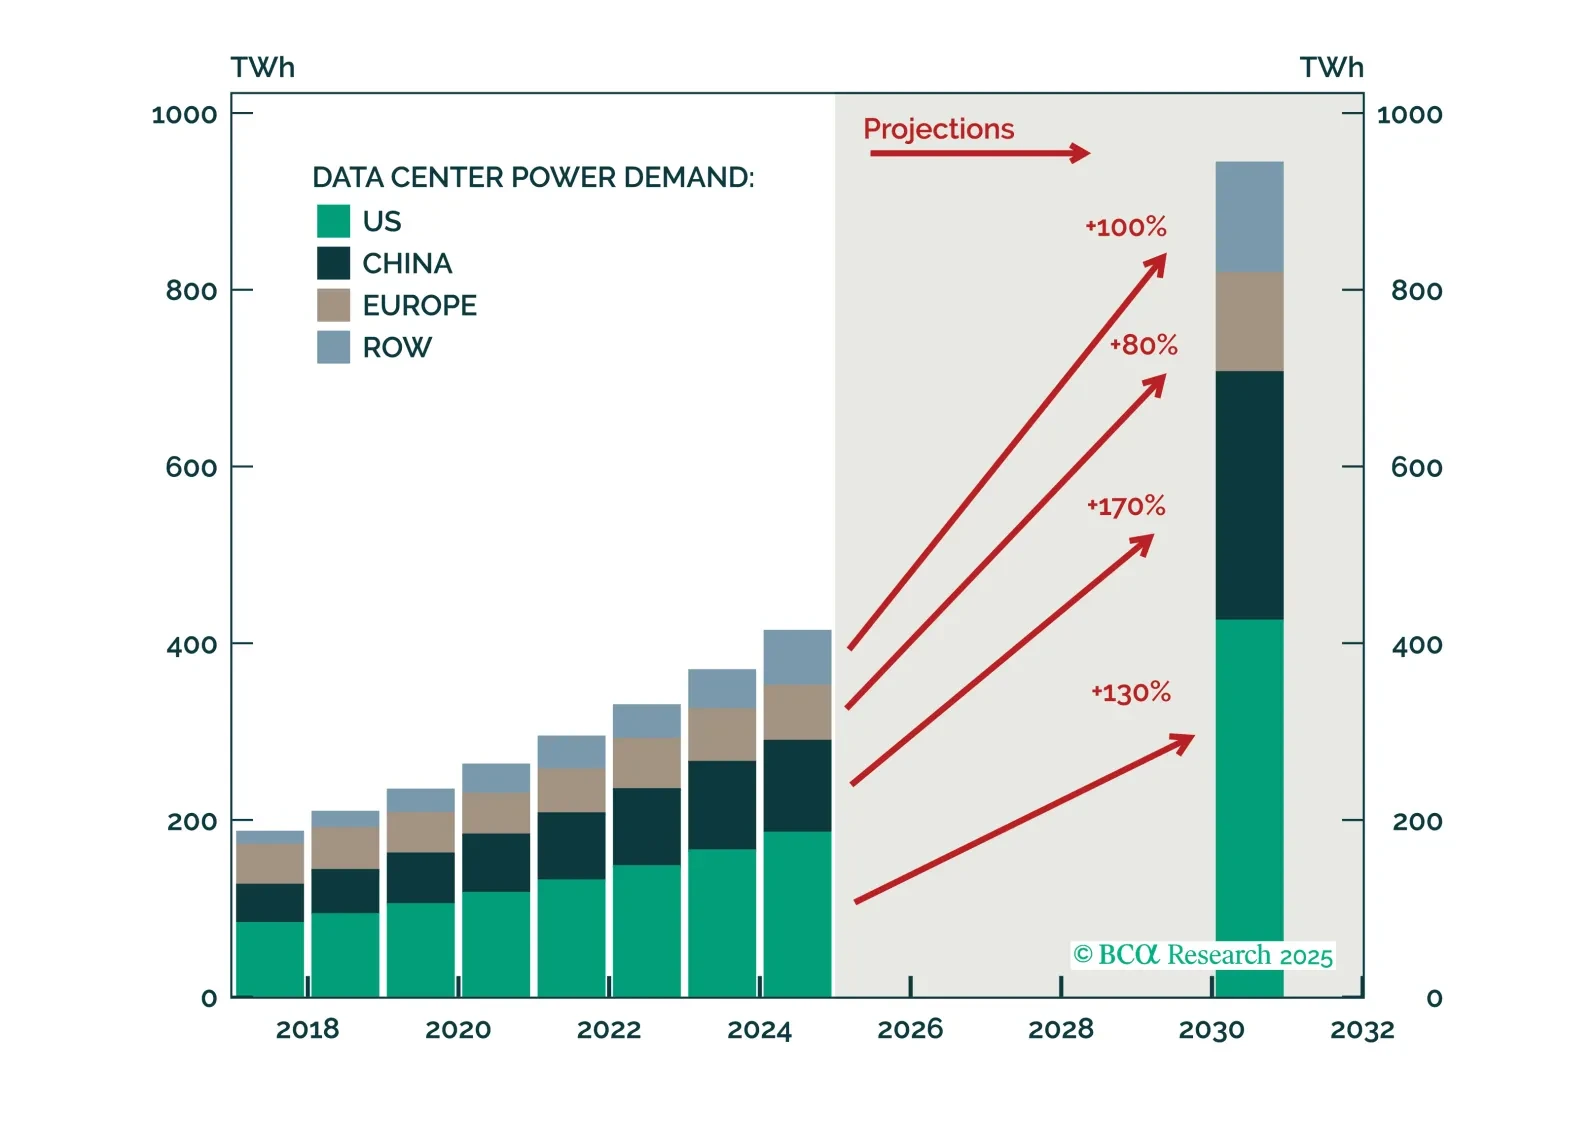
Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.
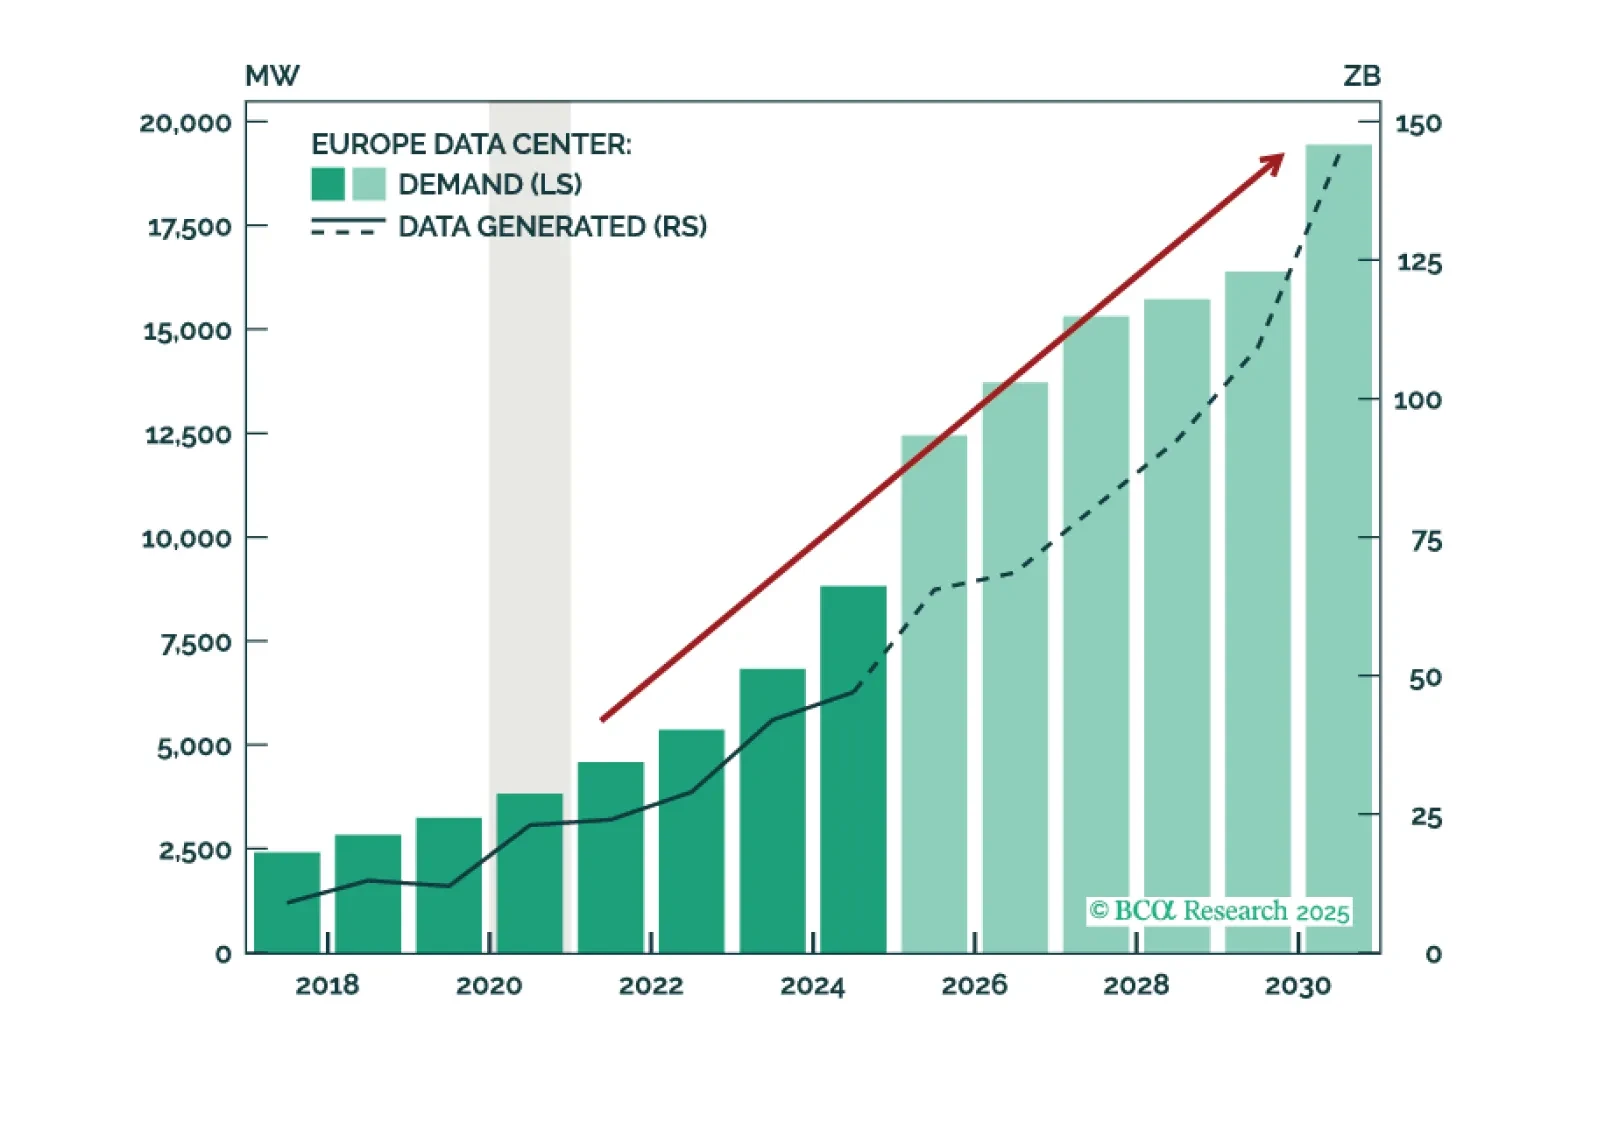
While the US is the pioneer, Europe will follow suit—more rapidly than expected. It is not a question of if GenAI will boom in Europe, but when. Europe’s Data Center growth is already strong today, but a US-style boom is just around the corner.

While AI deployment creates compelling investment opportunities, hyperscale facilities are not the only path forward. Investors should consider Office conversions into colocation Data Centers as the next dollar opportunity.