 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
The Chinese manufacturing sector has remained under downward pressure, but the stress level has alleviated compared to a few months ago. The Chinese labor market will likely continue to deteriorate, which will force policymakers to stay accommodative. Despite the recent rally, Chinese investable stocks remain exceptionally cheap.
The odds of an inflation "mini-scare" are rising, although deflationary tail risks from abroad cannot be dismissed.
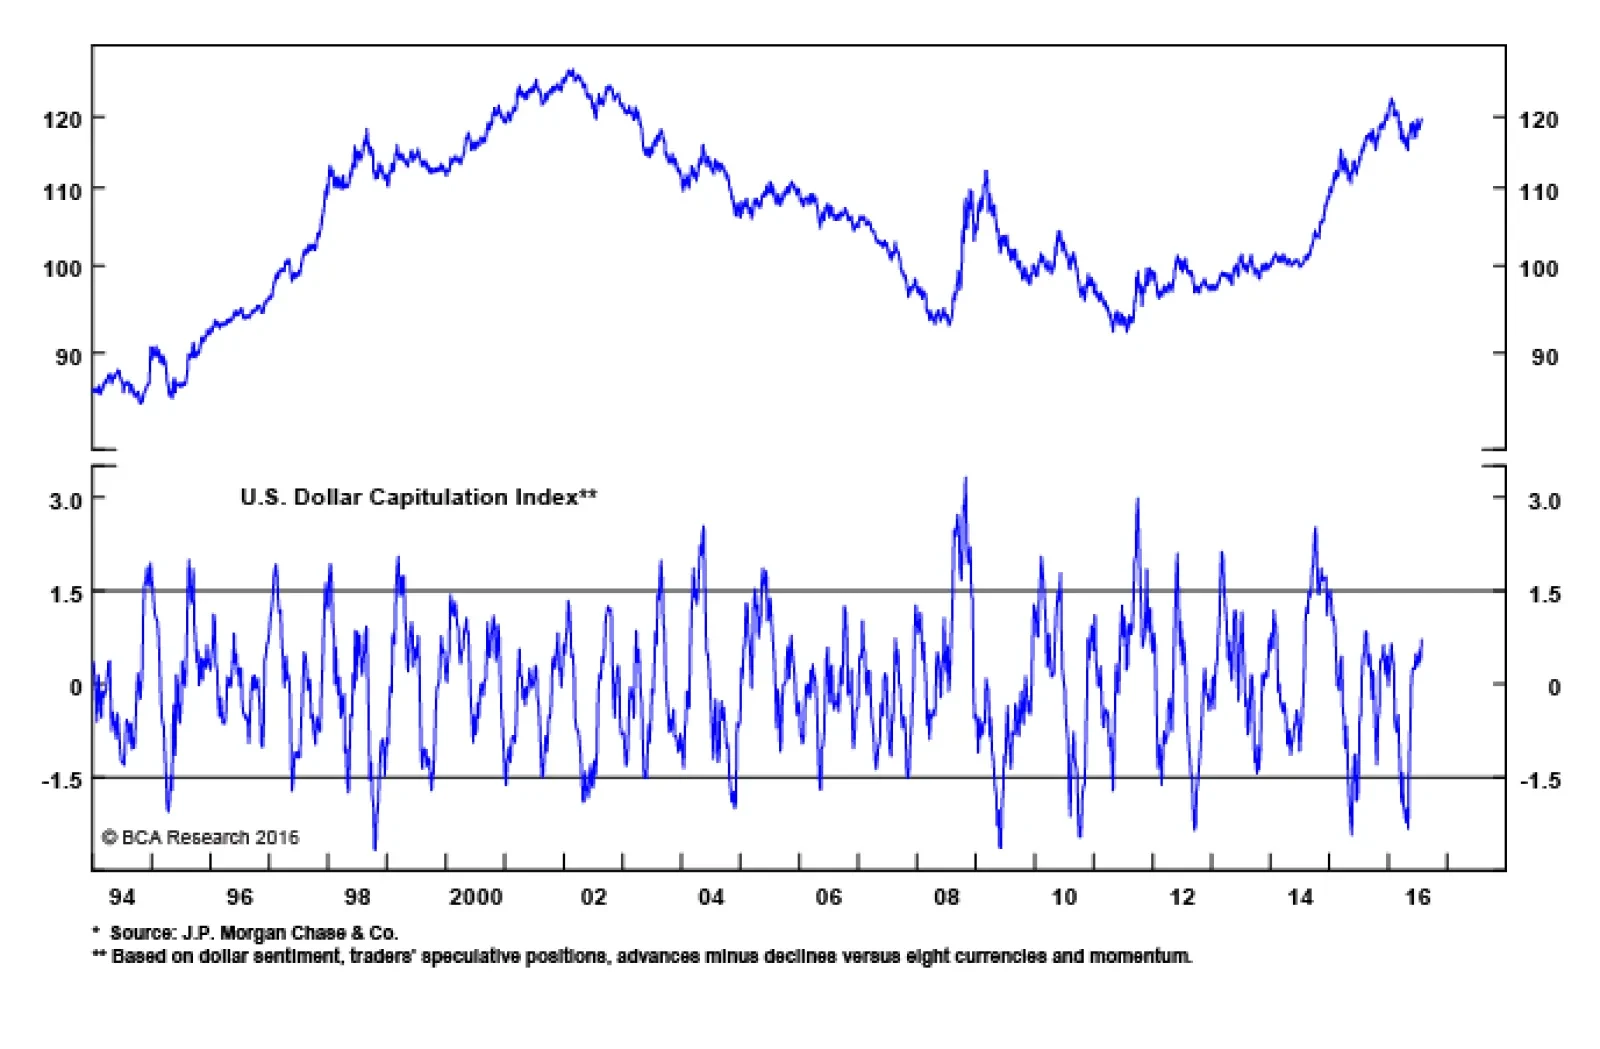
In July, the model outperformed both global equities and the S&P 500 in local-currency terms, while underperforming in U.S. dollar terms. For the monthly of August, the model made no changes to overall risk exposure.
The contours of a deal to solve Italy's banking problems are starting to emerge. This is good news for European risk assets. Nevertheless, reviving Italian growth will require even more ECB easing. The appetite for radical measures is low at present, but this will change if euro area growth remains lackluster and efforts by Japan to introduce helicopter money policies prove successful.
A collection of 10 important charts to monitor closely through the summer months.
The ongoing stampede into EM bonds is unsustainable. Running away from G7 bonds does not necessarily entail buying EM bonds. These are two separate investment decisions. Lower commodities prices, weaker EM currencies and higher G7 bond yields will undermine EM bond returns going forward. A new relative bond trade: long Polish and Hungarian 5-year / short South African and Turkish 5-year local bonds, currency unhedged.
The major banks are more willing to lend to the consumer and less willing to lend to the corporate sector.
In successful investment analysis "less is more, and usually much more effective."