Latest from BCA Research
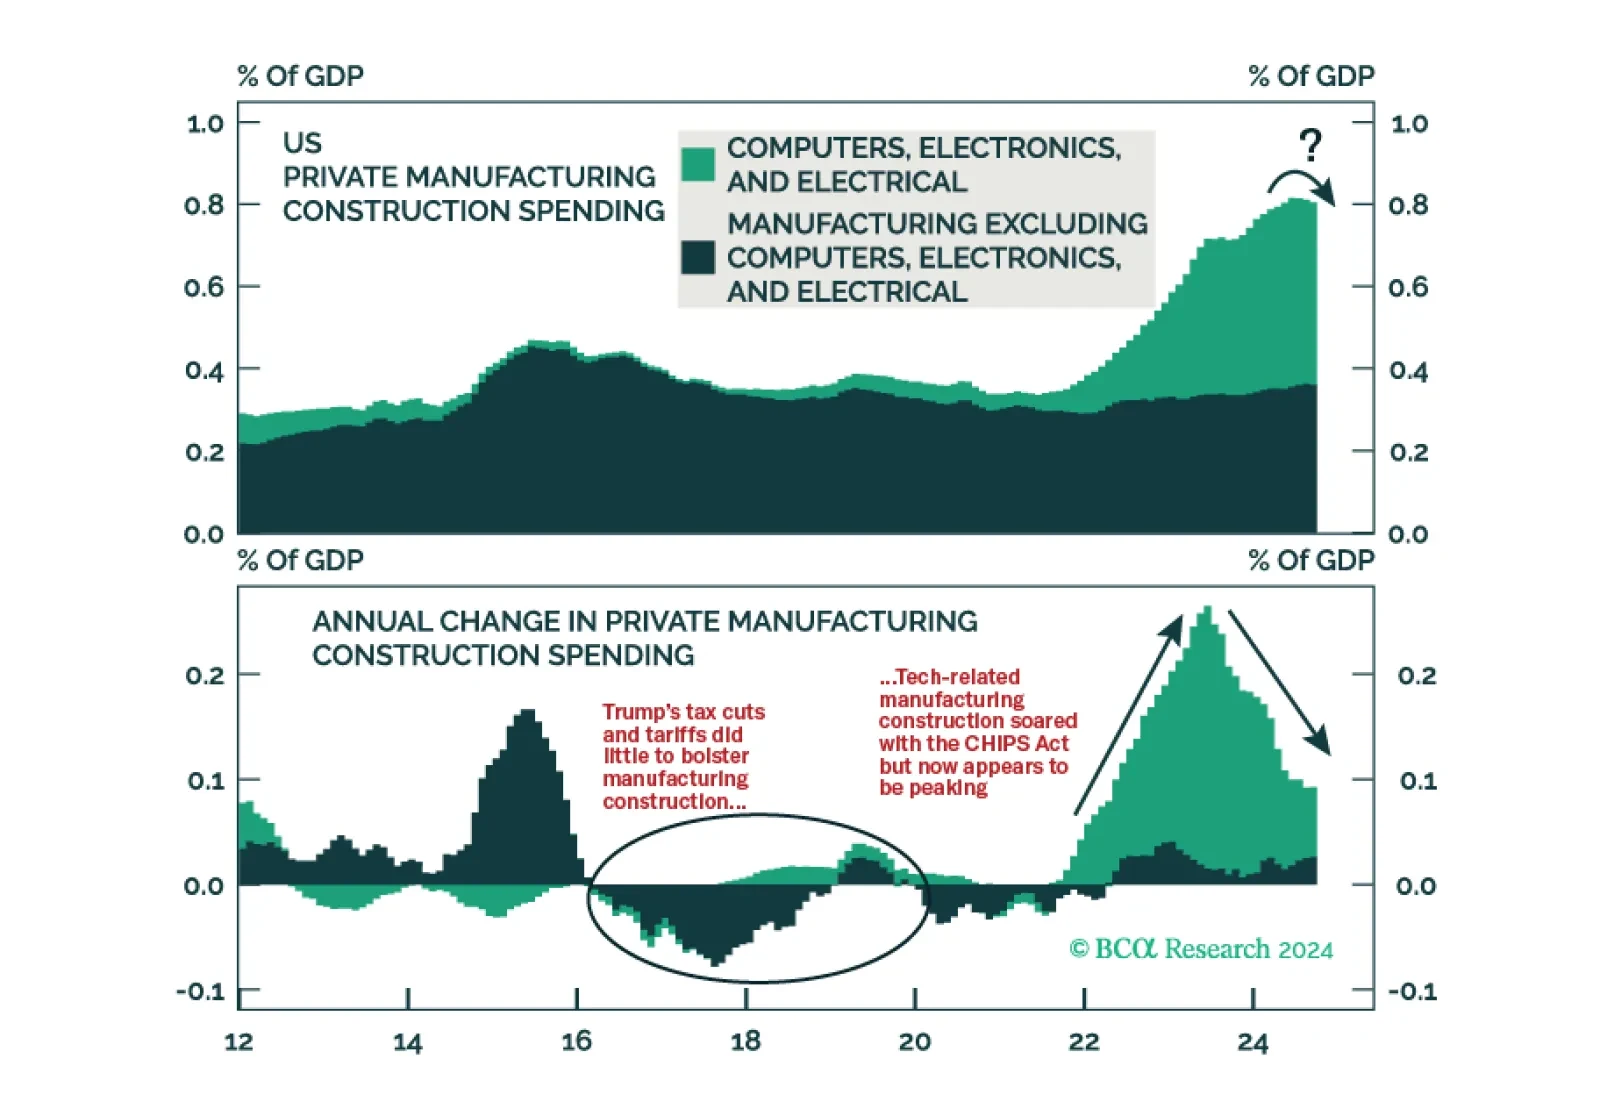
The prospect of a new trade war more than offsets the other pro-business parts of Trump’s agenda. With the labor market already weakening going into the election, we are raising our 12-month US recession probability from 65% to 75%.
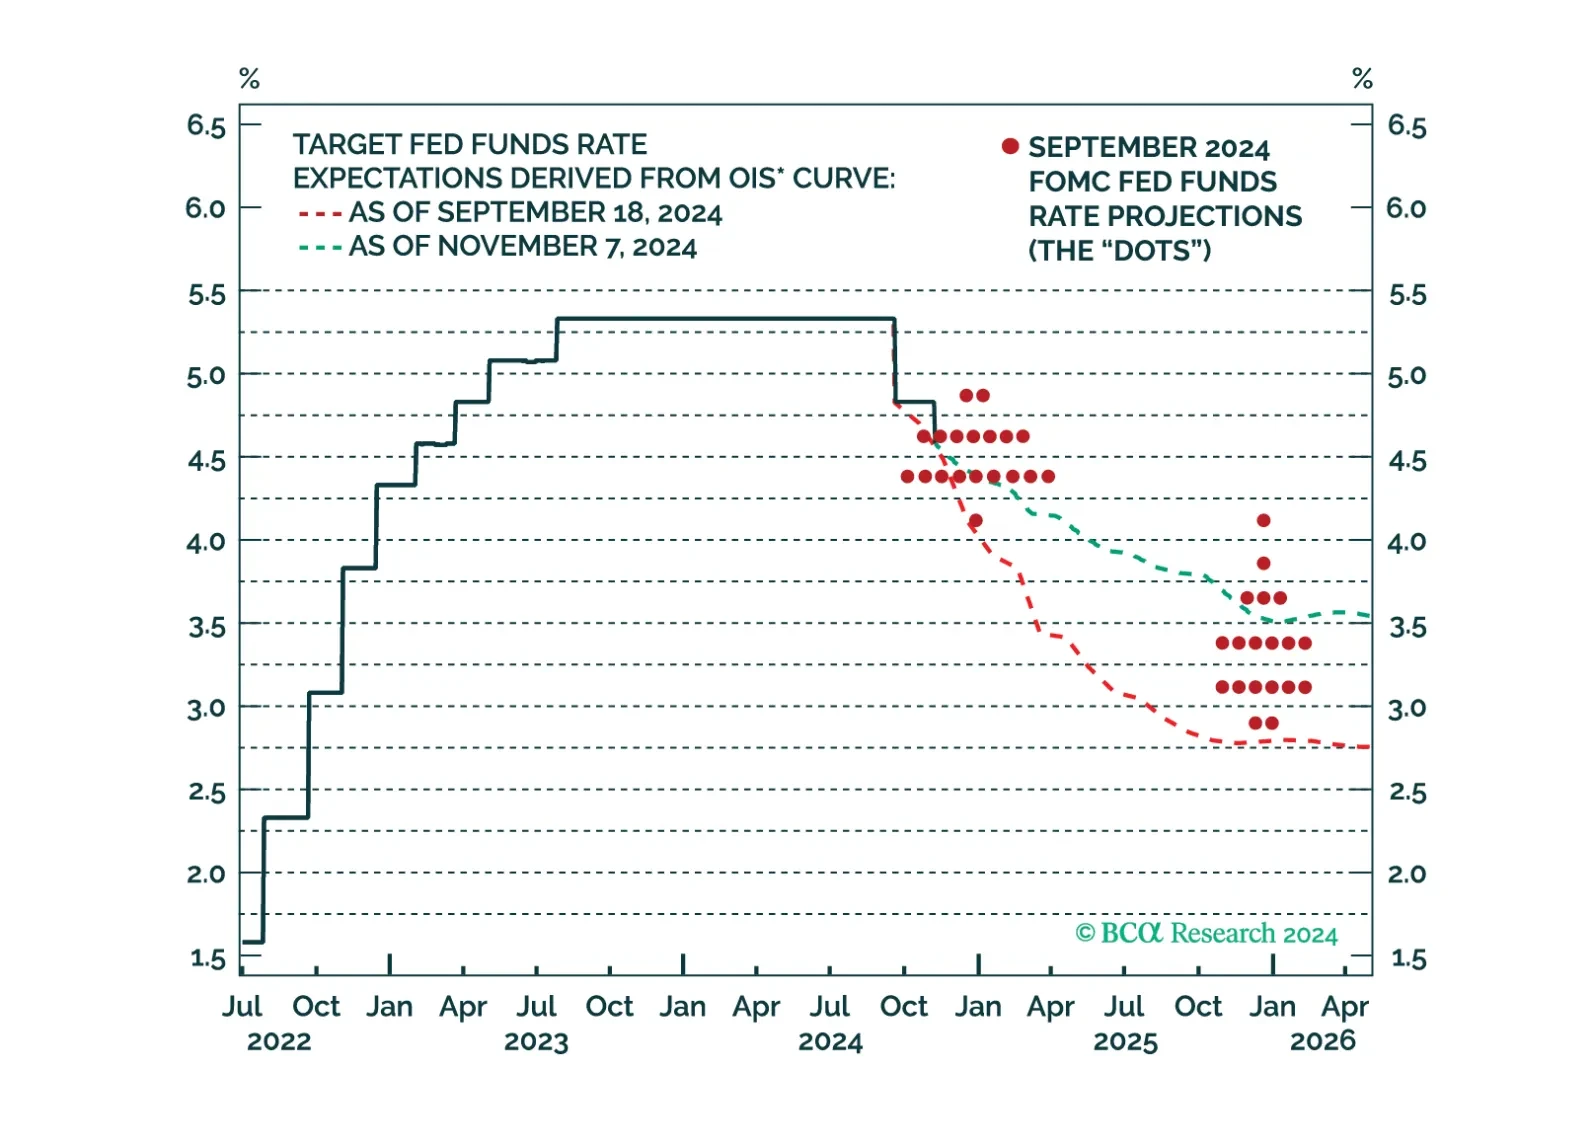
Our thoughts on the bond market’s reaction to the election and this afternoon’s FOMC meeting.
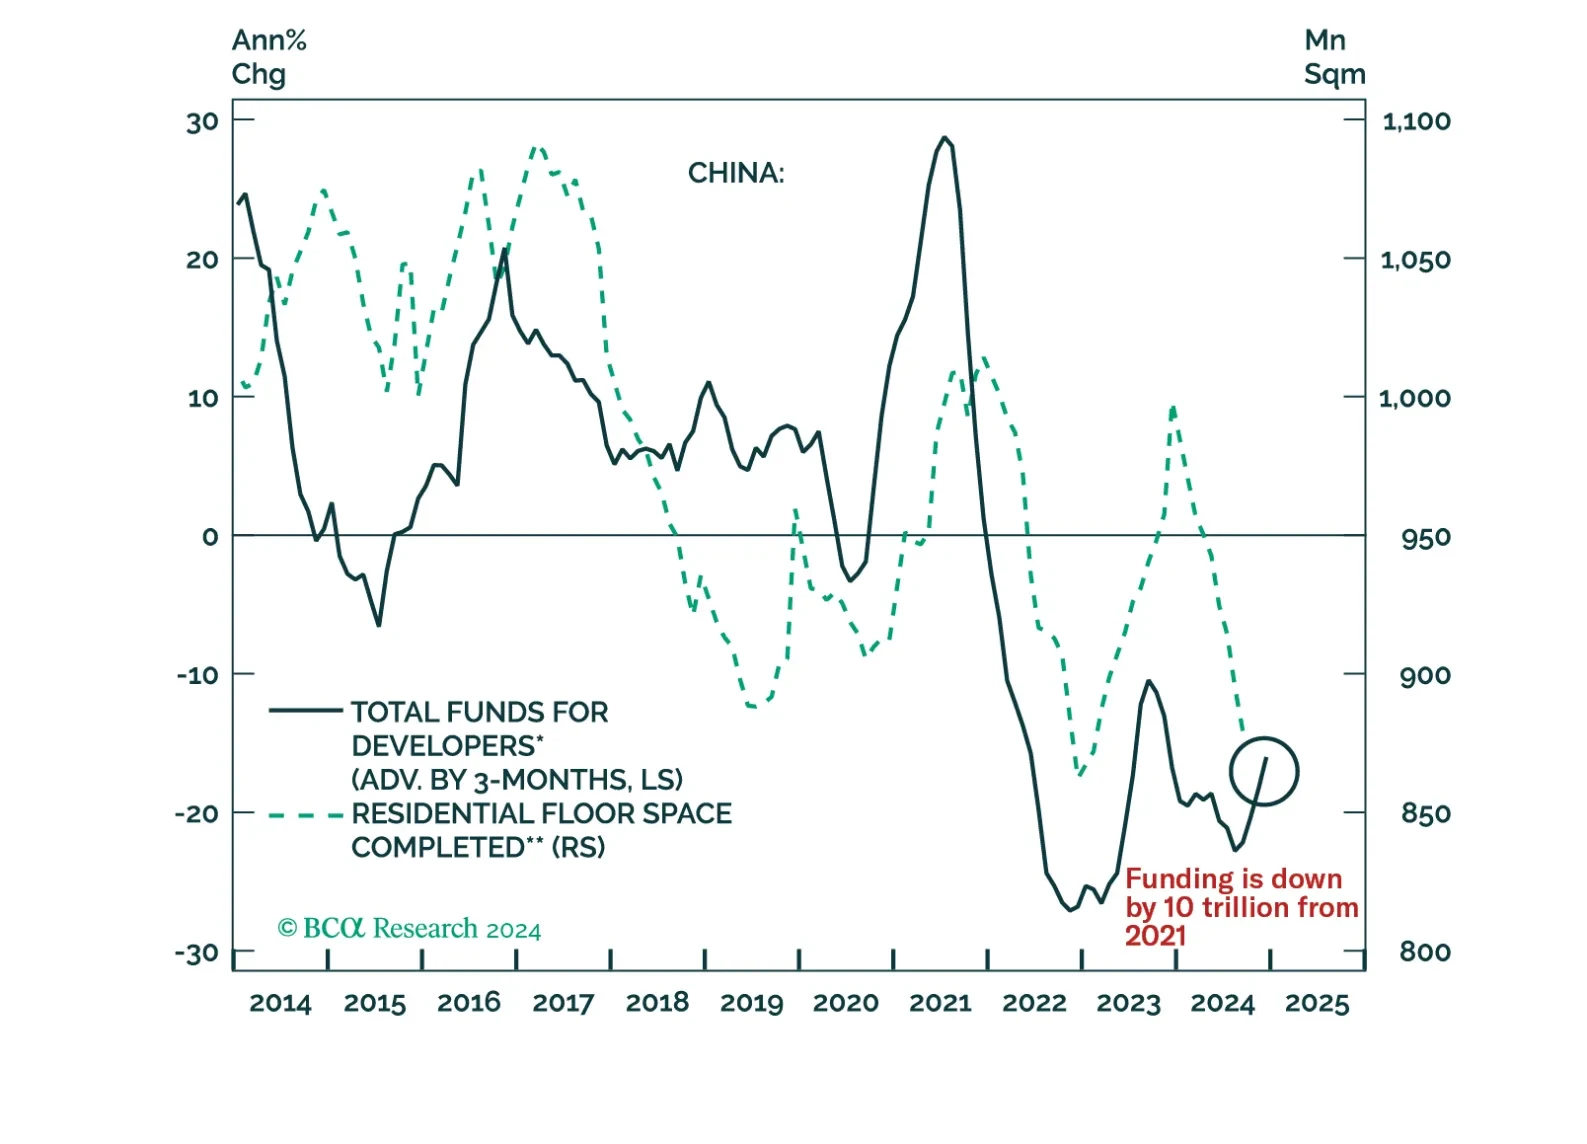
We spent last week visiting our clients in China. In this report, we share some of the key questions from the client meetings as well as our responses.
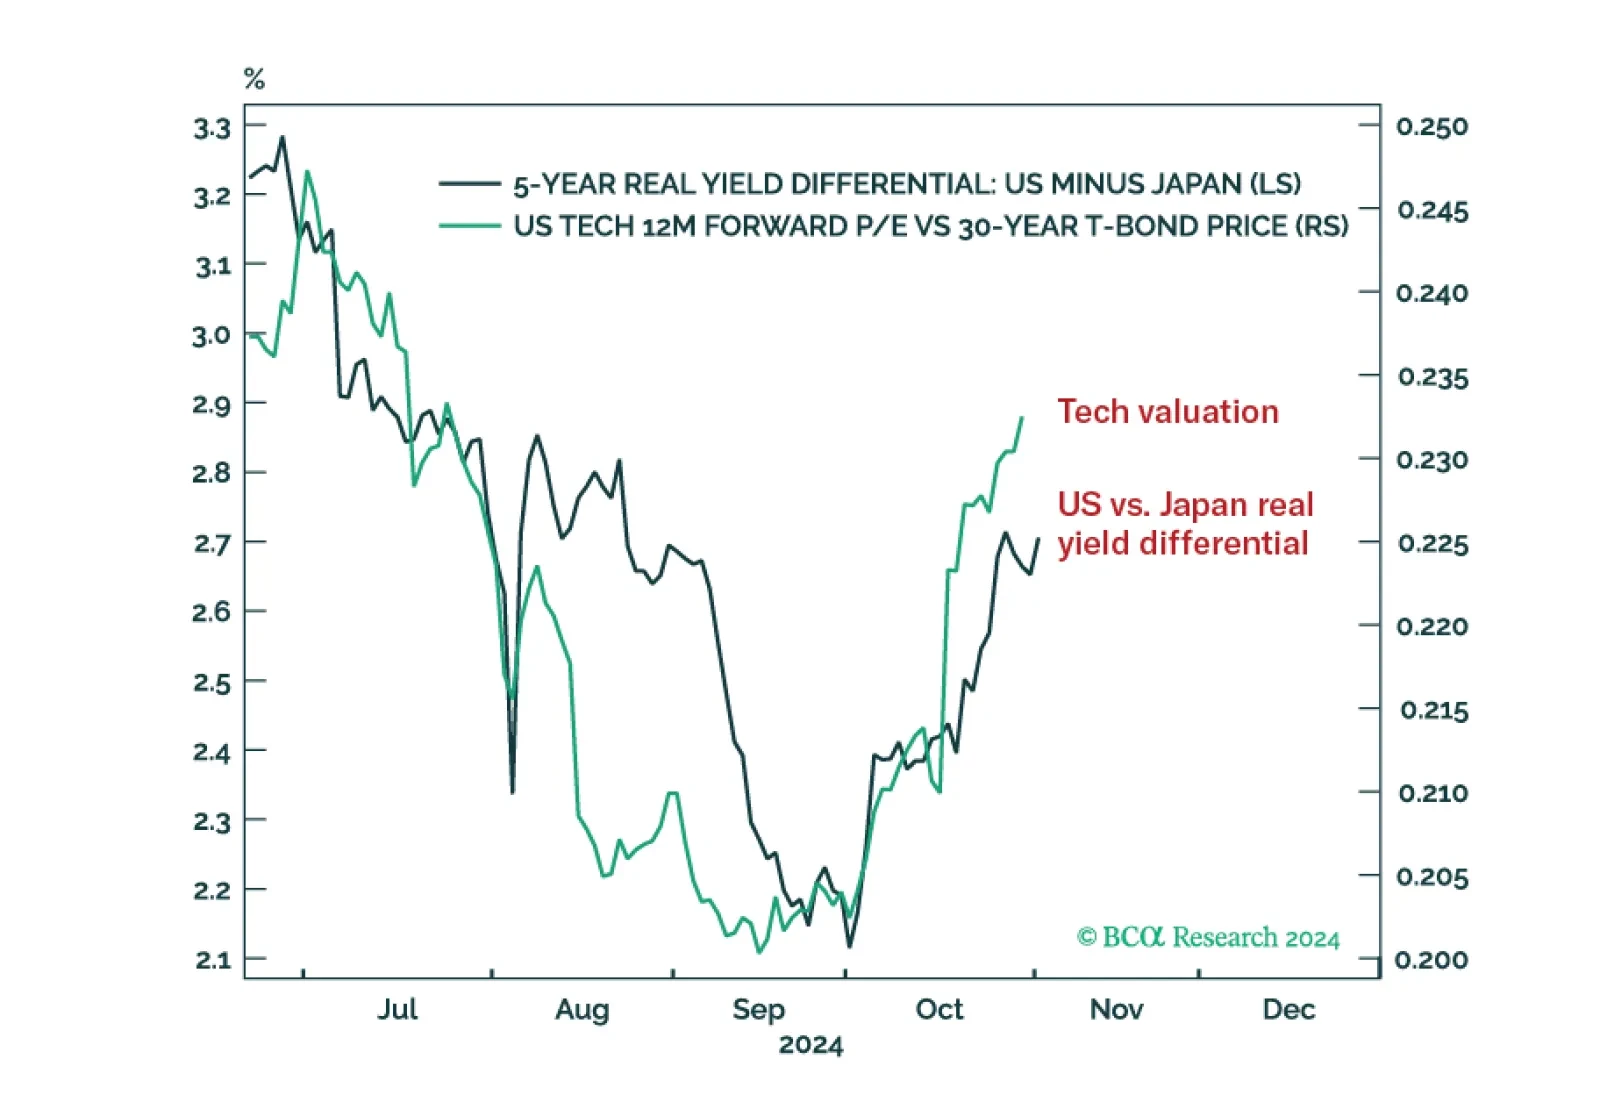
The most important transmission mechanism of a Trump presidency on the stock market will be via its impact on the US-Japan real yield differential. This is because Japan’s extreme negative real yield versus the US is the dominant source of global liquidity right now, and thereby the main driver of stock market valuation. In the short term therefore, higher US bond yields mean higher stock prices. The longer-term implications are more concerning though.

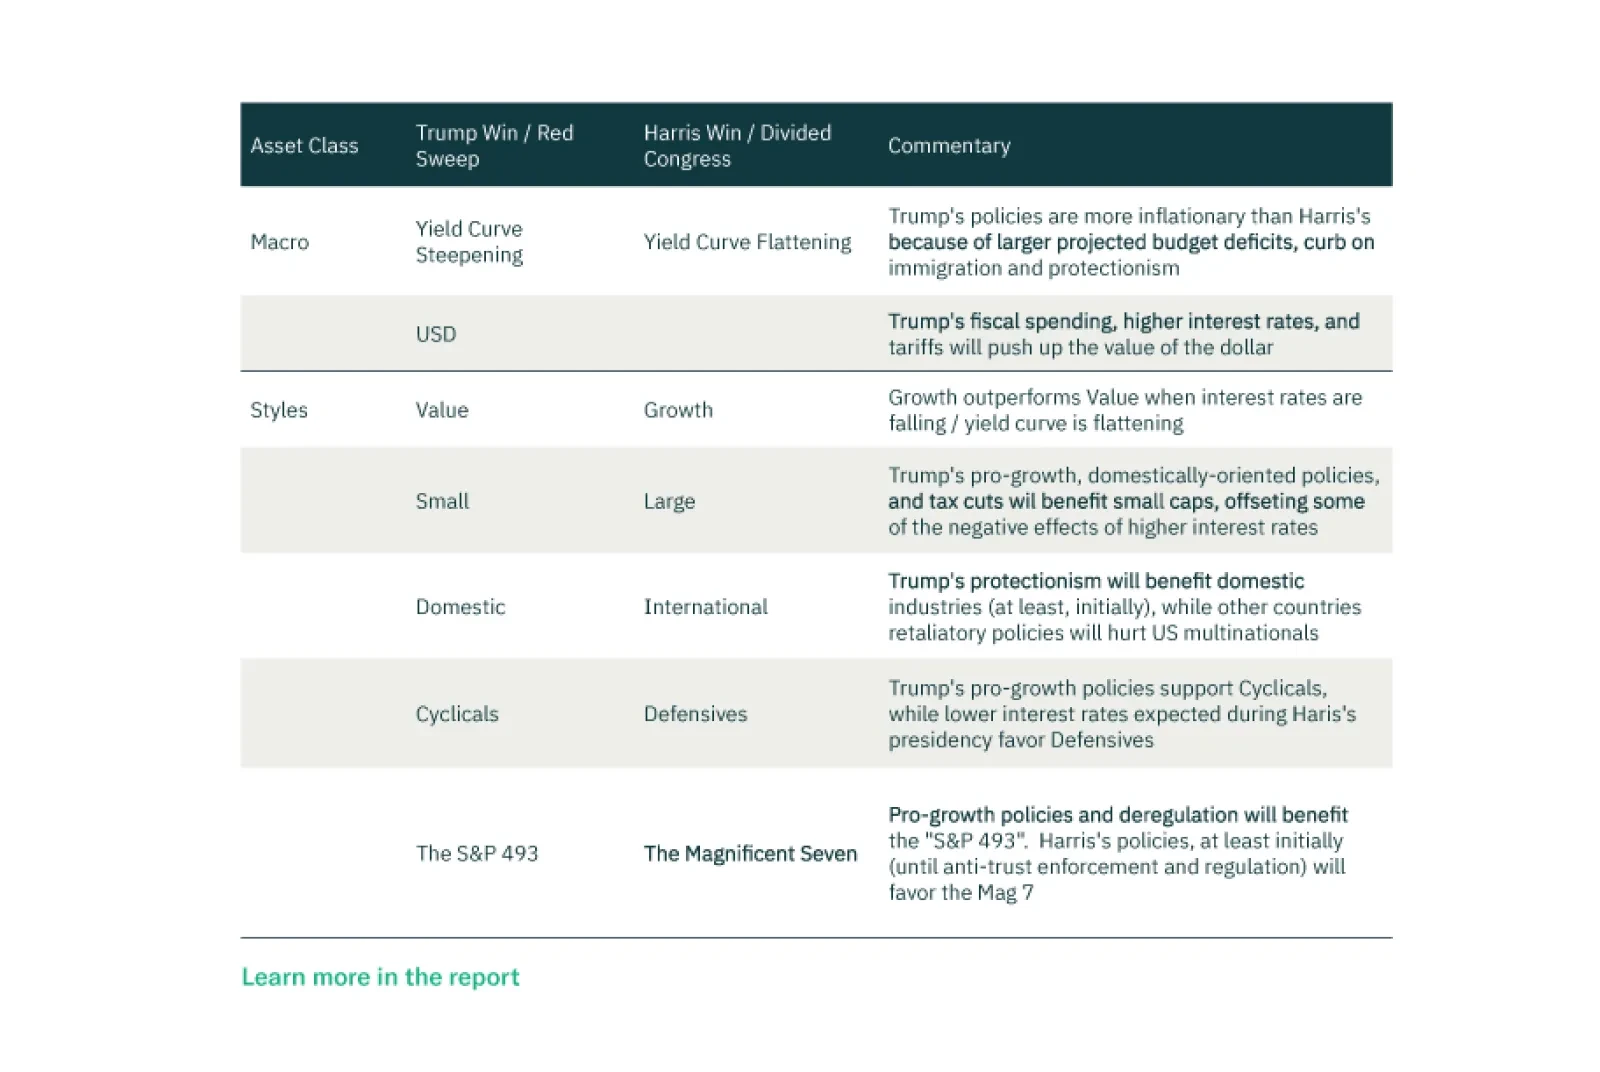
The most likely outcomes for the US elections are a “Red Sweep” and a “Blue Gridlock.” The following is a brief discussion of likely policies associated with each election outcome. We also present a post-election US Equities Cheat Sheet, in which we summarize winning trades for each scenario over the tactical investment horizon.
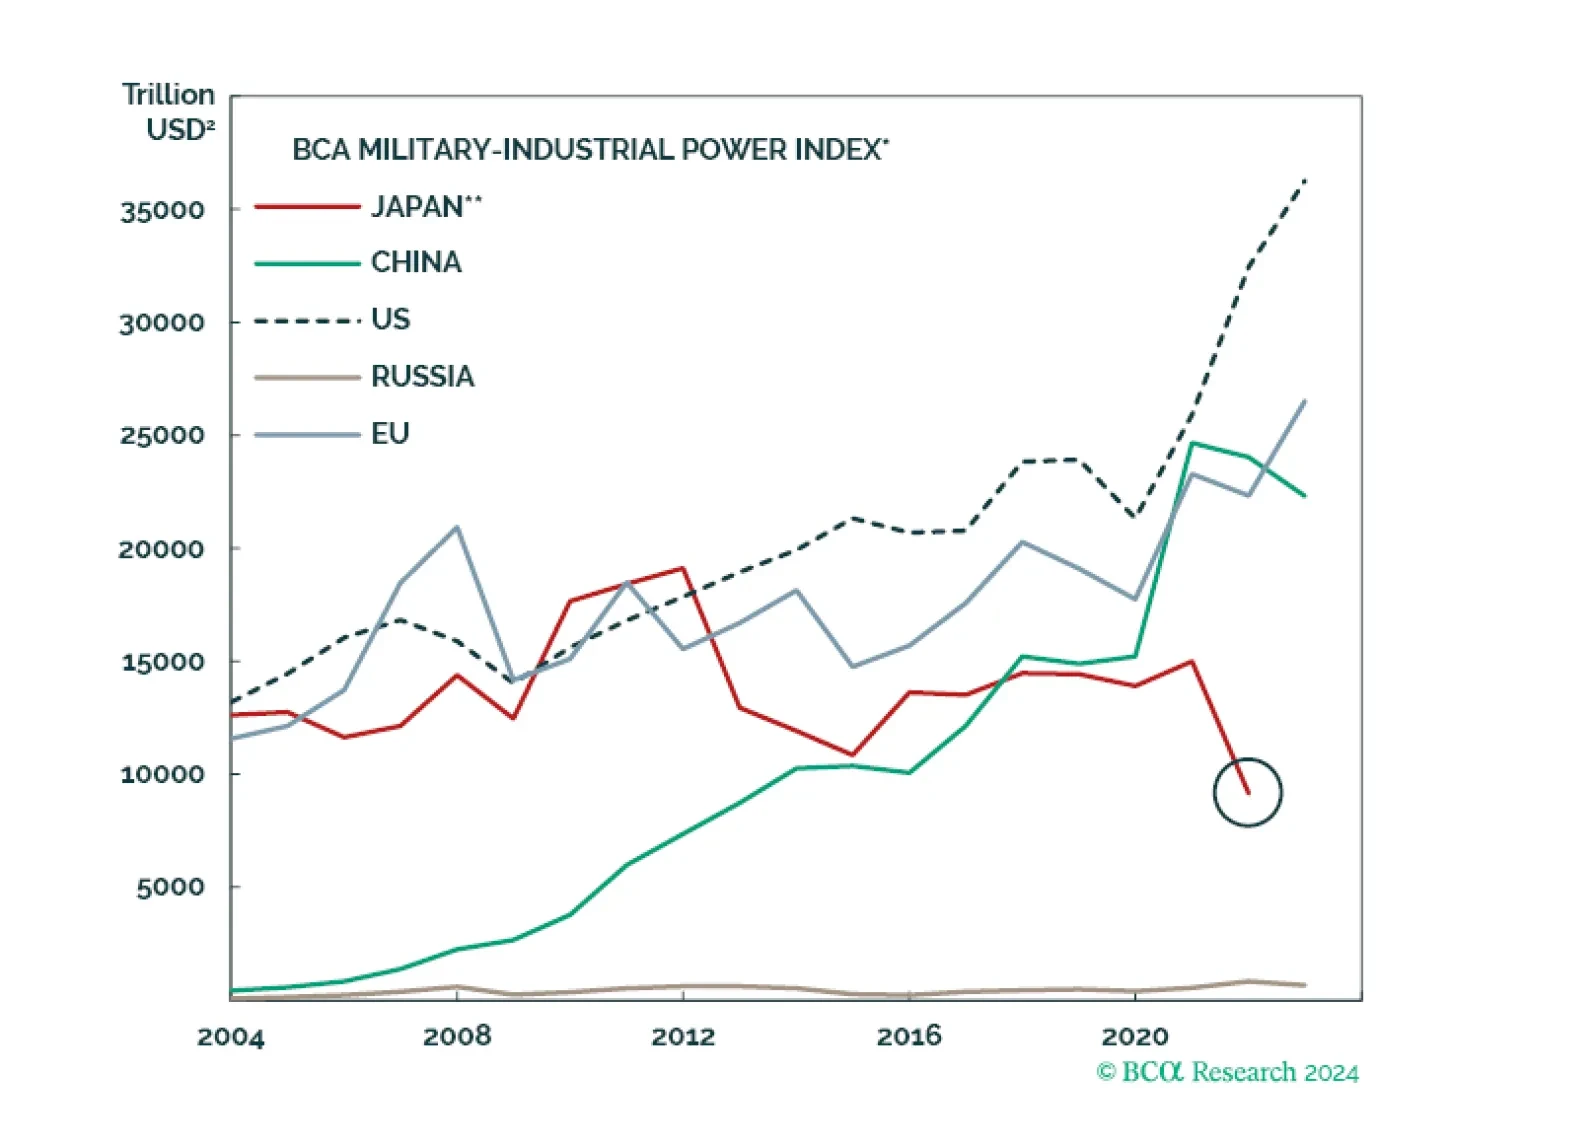
Over the next few months, Japan’s new government will ease fiscal policy, which will improve domestic demand on the margin. Monetary policy may tighten further in the short run but not too much over the long run. The geopolitical setting drives Japan into accommodative economic policy.

The Election Day is finally upon us. No, there is no final “silver bullet” forecast contained in this email. Just our long-term forecast of how the election will, no matter who wins, impact the markets.

Turkey has a path toward sustained disinflation. But that will require tight macro policies for an extended period. The question is, will the authorities tolerate the consequent growth slowdown, even a recession, and surging unemployment, as the necessary cost to break the back of inflation?
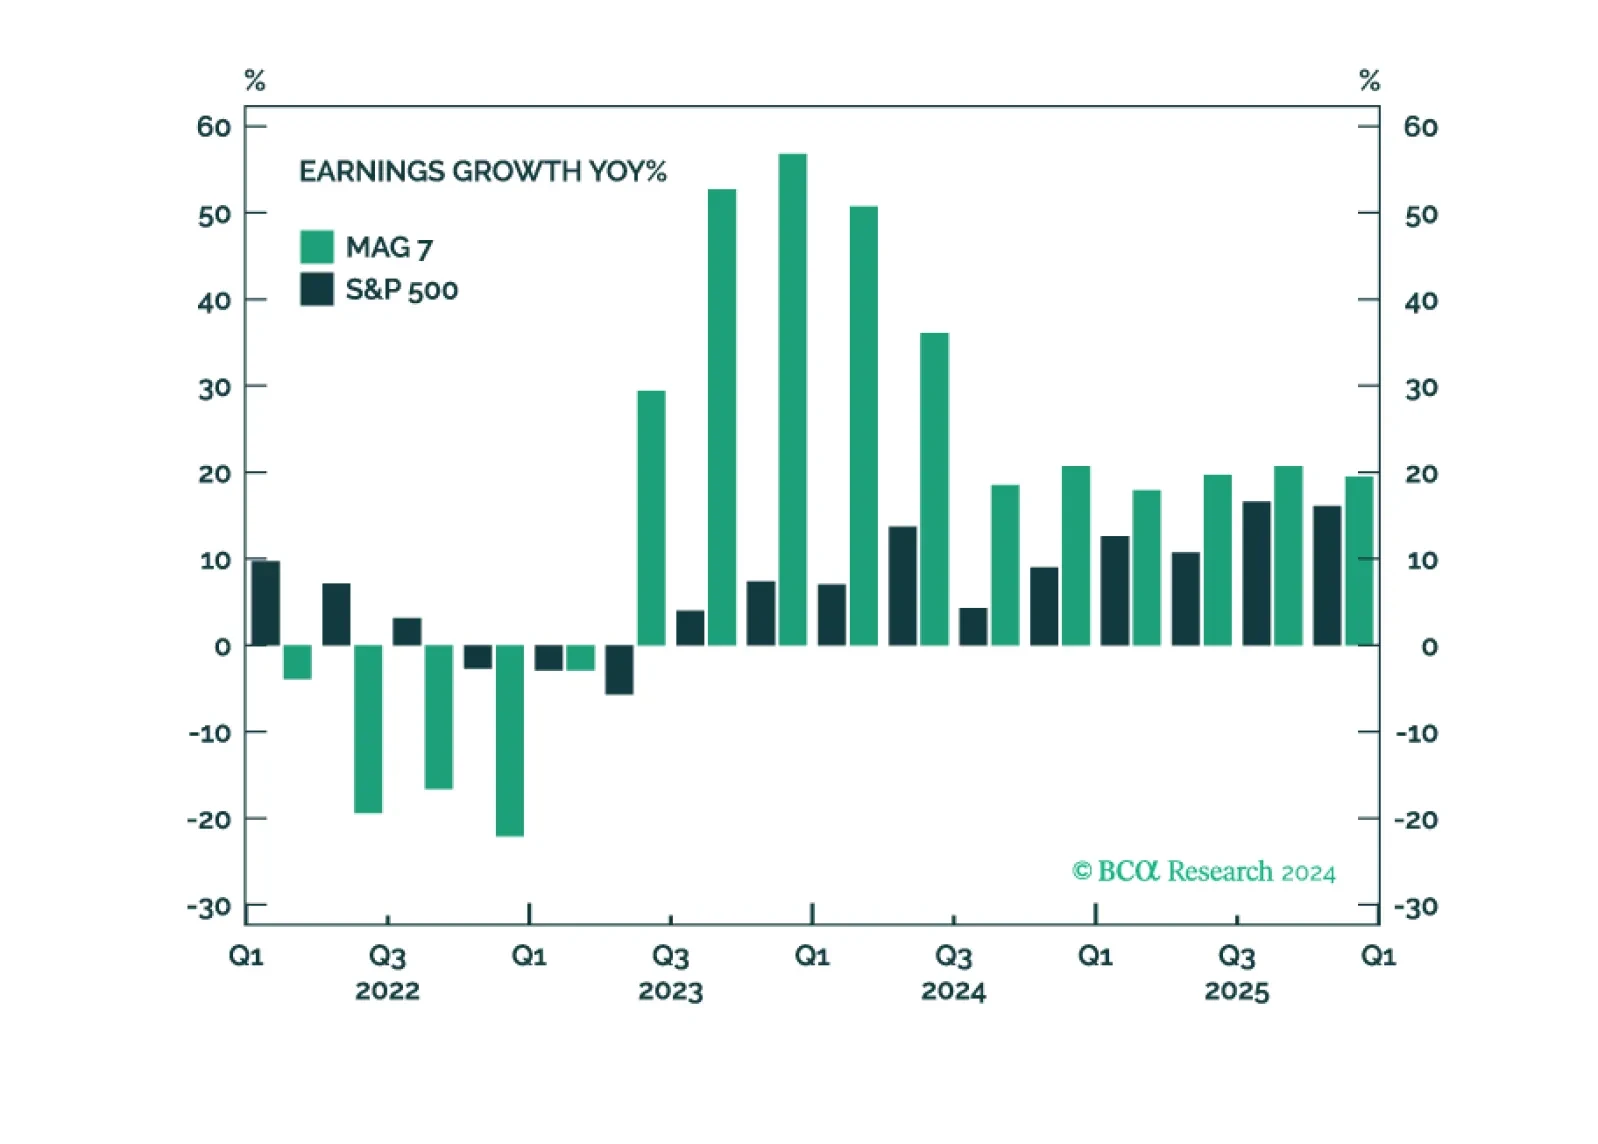
This week, we are sending you a sector chart pack. In the front section of this publication, we briefly review October's performance and then switch our attention to the earnings season and outlook for the Magnificent Seven.